| Investment | ₹300 CrManak Tabra-2 |
|---|---|
| Market Cap | ₹5,415.8 CrMid-range Performer |
| Revenue TTM | ₹1,172.8 CrOperating |
| RSI | 39.1Neutral Zone |
Key highlights
- Commercial production at the Manak Tabra-2 plant commenced on September 22, 2026
- Total investment for the new manufacturing facility is approximately Rs 300 crore
- Project adds 60,000 tonnes per annum of laminate manufacturing capacity
- Expansion adds 5.25 crore square meters per annum (01mm thickness) to existing output
- Entire expansion project was financed through the company's internal accruals
- New facility adjoins the company's existing plant in Manak Tabra, Panchkula
Production Commenced — What It Means
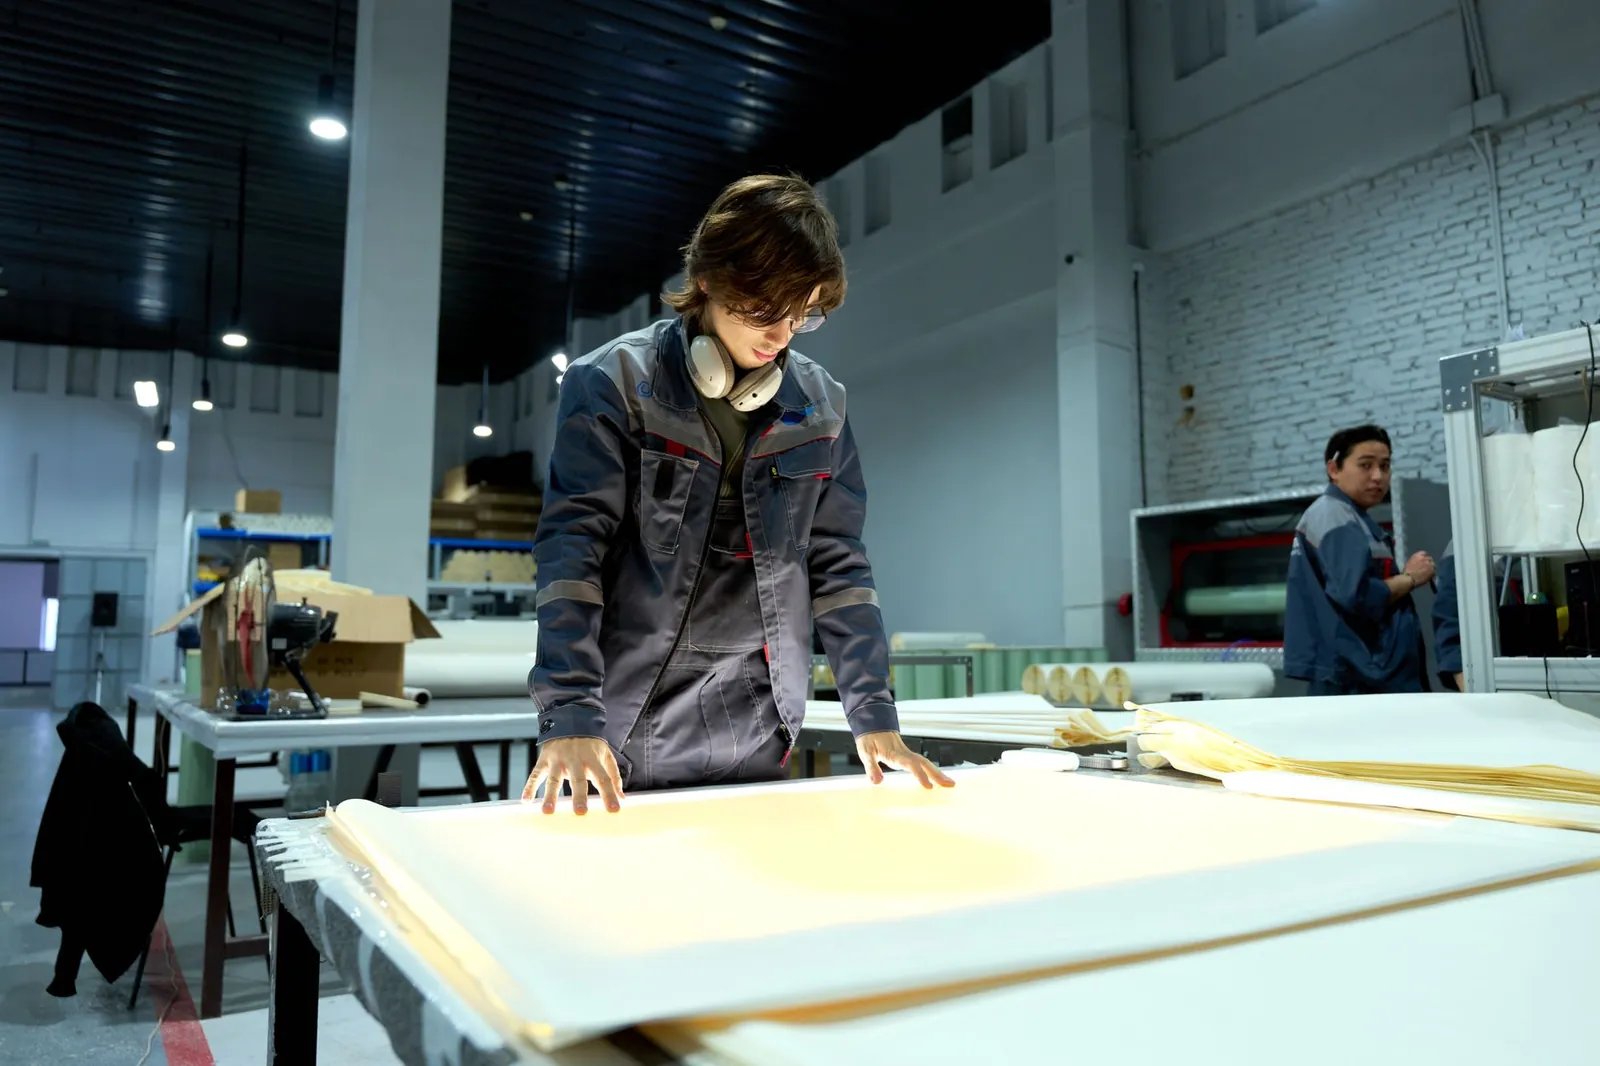
Stylam Industries has reached a major operational milestone with the commencement of commercial production at its Manak Tabra-2 facility in Panchkula, Haryana. This new plant adds approximately 5.25 crore square meters of annual manufacturing capacity, equivalent to 60,000 tonnes of laminates. This addition follows a previous announcement in early 2024 regarding the development of this site adjacent to existing units.
By bringing this new plant online, the company is positioning itself to capture a larger share of the domestic and international surfacing market, specifically targeting the 01mm thickness laminate segment.
Path to This Milestone
- The project was first intimated in January 2024 as a greenfield/brownfield extension in Haryana
- Total project outlay was approximately Rs 300 crore, reflecting significant capital commitment
- Expansion was funded entirely through internal accruals, maintaining a stable debt profile
- The new unit scales the company's aggregate tonnage capacity from 80,000 to 1,40,000 tonnes per annum
- The facility supports the rationale of enhancing manufacturing depth to cater to growing demand
Financial Context and Revenue Impact
Prior to this expansion, Stylam Industries was operating at approximately 90% capacity utilization at its Panchkula and Manak Tabra-1 facilities. With the existing 80,000-tonne capacity heavily utilized, the new 60,000-tonne facility provides critical headroom for volume growth. The company reported a TTM revenue of Rs 1,172.78 crore and a net profit growth of 70.35% YoY in the most recent quarter.
Given the high utilization levels of its previous assets, this 75% increase in tonnage capacity is expected to be a primary driver for future top-line expansion and operational leverage.
Business Overview and Sector Tailwinds
Stylam Industries is a leading player in the forest products sector, recognized as a Star Export House by the Government of India. The company manufactures a wide range of premium surfacing products including High-Pressure Laminates (HPL), acrylic solid surfaces, and specialty exterior cladding. The Indian laminate industry is currently benefiting from robust demand in the residential real estate sector and a growing trend toward premium interior finishes.
Furthermore, as an established exporter, Stylam is well-positioned to leverage the 'China Plus One' strategy adopted by global furniture and interior decor manufacturers.
| Share price | ₹3195.5 |
|---|---|
| Market capitalisation | ₹5,415.77 Cr |
| Revenue (annual) | ₹1,129.29 Cr |
| Net profit (annual) | ₹149.87 Cr |
| Revenue (latest quarter) | ₹326.47 Cr+15.38% vs previous quarter |
| Net profit (latest quarter) | ₹48.16 Cr+25.93% vs previous quarter |
| P/E (TTM) | 31.9×Sector 44.66× |
| Promoter holding | 56.86%+2.75% QoQ |
| FII holding | 2.62%Current quarter |
Reference market data from a third-party provider, as of the story. Not a valuation or a recommendation.
Exchange filing by Stylam Industries Ltd announcing the commencement of commercial production at its new laminate plant in Panchkula. Market figures from a third-party data provider.