| Net Profit Qtr | ₹53.4 Cr130.9% YoY Growth |
|---|---|
| Revenue Qtr | ₹1,045.3 CrRecord Milestone |
| Market Cap | ₹3,058.5 CrStrong Performer |
| PE TTM | 20.15Sector PE 34.25 |
Key highlights
- Revenue grew 33% YoY to ₹1,045.32 crore with record EBITDA of ₹127 crore
- Net profit surged 130.9% YoY to reach a record ₹53.4 crore for the quarter
- H1 FY27 PAT stands at ₹94 crore, already exceeding the total profit for full-year FY26
- Management reiterated the aspiration to double the company's PAT in FY27 over the previous fiscal
- Renewable energy mix reached 35%, with a roadmap to hit 70% by Q1 FY28 for cost optimization
Historic Performance Driven by Capacity Utilization
Sangam India reported that Q2 FY27 was the best quarter in its history, supported by high capacity utilization across all manufacturing divisions. Quarterly revenue reached ₹1,045 crore, representing a 33% increase over the same period last year. The company's profitability saw sharp expansion, with net profit hitting ₹53.4 crore, while EBITDA reached ₹127 crore.
Efficiency gains were reflected in the balance sheet, with return on equity improving to nearly 14% from approximately 4% two years ago. Operating profit margins stood at 11.6% this quarter, compared to 9.8% in the corresponding period of the previous year.
Strategic ₹1,500 Crore Capex and Capacity Roadmap
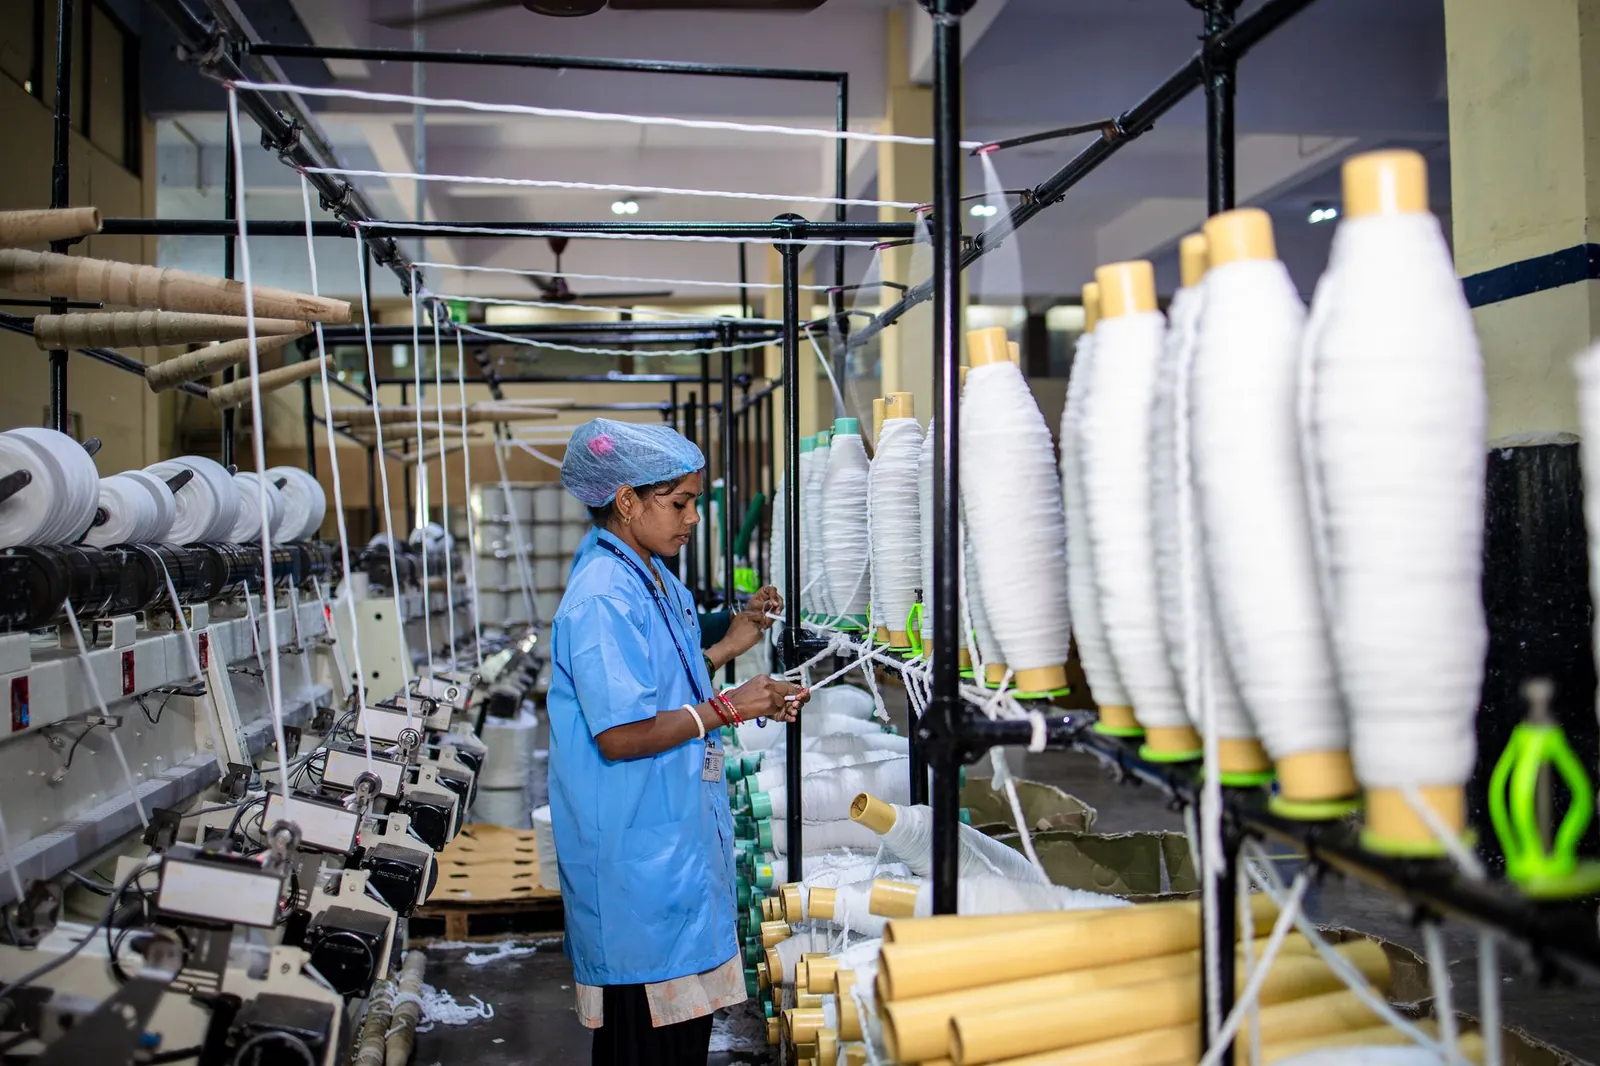
- Ongoing ₹1,500 crore capex plan focused on spinning and forward garmenting integration
- Planned 60% to 70% capacity addition in the cotton yarn segment in terms of quantity
- Approximately 40% to 50% of new capacity to be utilized captively for in-house denim fabrics
- Garmenting utilization reached 37% this quarter, with a target of 50-60% for the full year
- Targeted completion date for the massive manufacturing expansion is set for March 31, 2029
- Renewable power capacity is projected to stabilize at 70% by June 2027, unlocking ₹50-60 crore in annual savings
Management Perspective on Profit Trajectory
In April, I said we aspire to double our PAT this year. At the halfway mark, I am happy to say we are well on that path. Capacity utilization remains high across all our divisions today.
Rising Debtor Days and Government Tender Focus
Despite record revenue, the company noted a rise in debtor days to 77 days in September, up from 67 days in March. This shift is primarily attributed to a focused push into government tenders, which accounted for nearly ₹200 crore in sales during the first half of the year. Management explained that while these tenders provide high volume, they operate on longer payment cycles.
Additionally, longer lead times for export shipments have contributed to the elongated working capital cycle. The company aims to bring these levels back to March 2026 levels by the end of the current fiscal year through bill discounting and factoring initiatives.
| Date | Announcement | Amount |
|---|---|---|
| 04 Nov 2026 | Q2 FY27 Consolidated Net ProfitSource: businessupturn.com | ₹53.40 Cr |
| 18 Jul 2026 | Q1 FY27 Consolidated Net ProfitSource: sahi.com | ₹41.02 Cr |
| 18 Jul 2026 | Management Guidance - Capex plan for garmenting integration and capacity expansion by March 2029Source: sahi.com | ₹1,500.00 Cr |
| 23 Apr 2026 | Management Guidance - FY27 target/aspiration to double PAT over FY26Source: fyers.in | – |
| 22 Apr 2026 | Q4 FY26 Consolidated Net ProfitSource: fyers.in | ₹32.90 Cr |
| 21 Jan 2026 | Q3 FY26 Consolidated Net ProfitSource: BSE filing | ₹24.51 Cr |
What to watch next
- Commissioning of renewable energy capacity to reach 50% by the end of FY27
- Reduction of debtor days toward the 67-day target by March 31, 2027
- Incremental benefits from spinning modernization expected to accrue starting April 2027
- Final commissioning of the ₹1,500 crore garmenting and expansion project by March 2029
“Revenue crossed a thousand crores in a quarter for the first time at 1,045 crores, up 33% over last year. EBITDA was 127 crores and PAT 53 crores, both the highest we have ever reported.”
“Our next focus is capacity, including modernizing and expanding our spinning and making more of our own raw materials. The work is on track and the larger benefits will start coming in from the next financial year.”
| Share price | ₹608.7 |
|---|---|
| Market capitalisation | ₹3,058.51 Cr |
| Revenue (annual) | ₹3,234.53 Cr |
| Net profit (annual) | ₹82.60 Cr |
| Revenue (latest quarter) | ₹1,045.32 Cr+21.50% vs previous quarter |
| Net profit (latest quarter) | ₹53.40 Cr+30.18% vs previous quarter |
| P/E (TTM) | 20.15×Sector 34.25× |
| Promoter holding | 70.52%0.00% QoQ |
| FII holding | 2.45%Current quarter |
Reference market data from a third-party provider, as of the story. Not a valuation or a recommendation.
Exchange filing by Sangam India Limited regarding its Q2 FY27 earnings conference call transcript and presentation. Market figures from a third-party data provider.