| Expansion Capex | ₹14,500 CrGrowth Program |
|---|---|
| Market Cap | ₹86,032 CrMid-range Performer |
| P/E TTM | 30.68xSector 32.24x |
| 1-Year Return | -38.44%Stock Performance |
| Execution period | through FY30 |
| Deal value | ₹14,500 Cr |
| Share of market cap | 16.9% |
| Share of annual revenue | 36.4% |
Key highlights
- New growth capex program of approximately ₹14,500 crore to add ~30 MTPA capacity
- Total cement capacity target set at 155 MTPA by FY30 from current 113.5 MTPA
- Expansion includes 15.5 MTPA in West Cluster and 11.6 MTPA in East Cluster
- Clinker capacity to increase by 10.3 MTPA across Assam, Maharashtra, and Gujarat
- Company aims to achieve a manufacturing cost of ₹4,000 per metric ton by FY28
| . | |
|---|---|
| . | |
| . |
A Massive ₹14,500 Crore Manufacturing Footprint
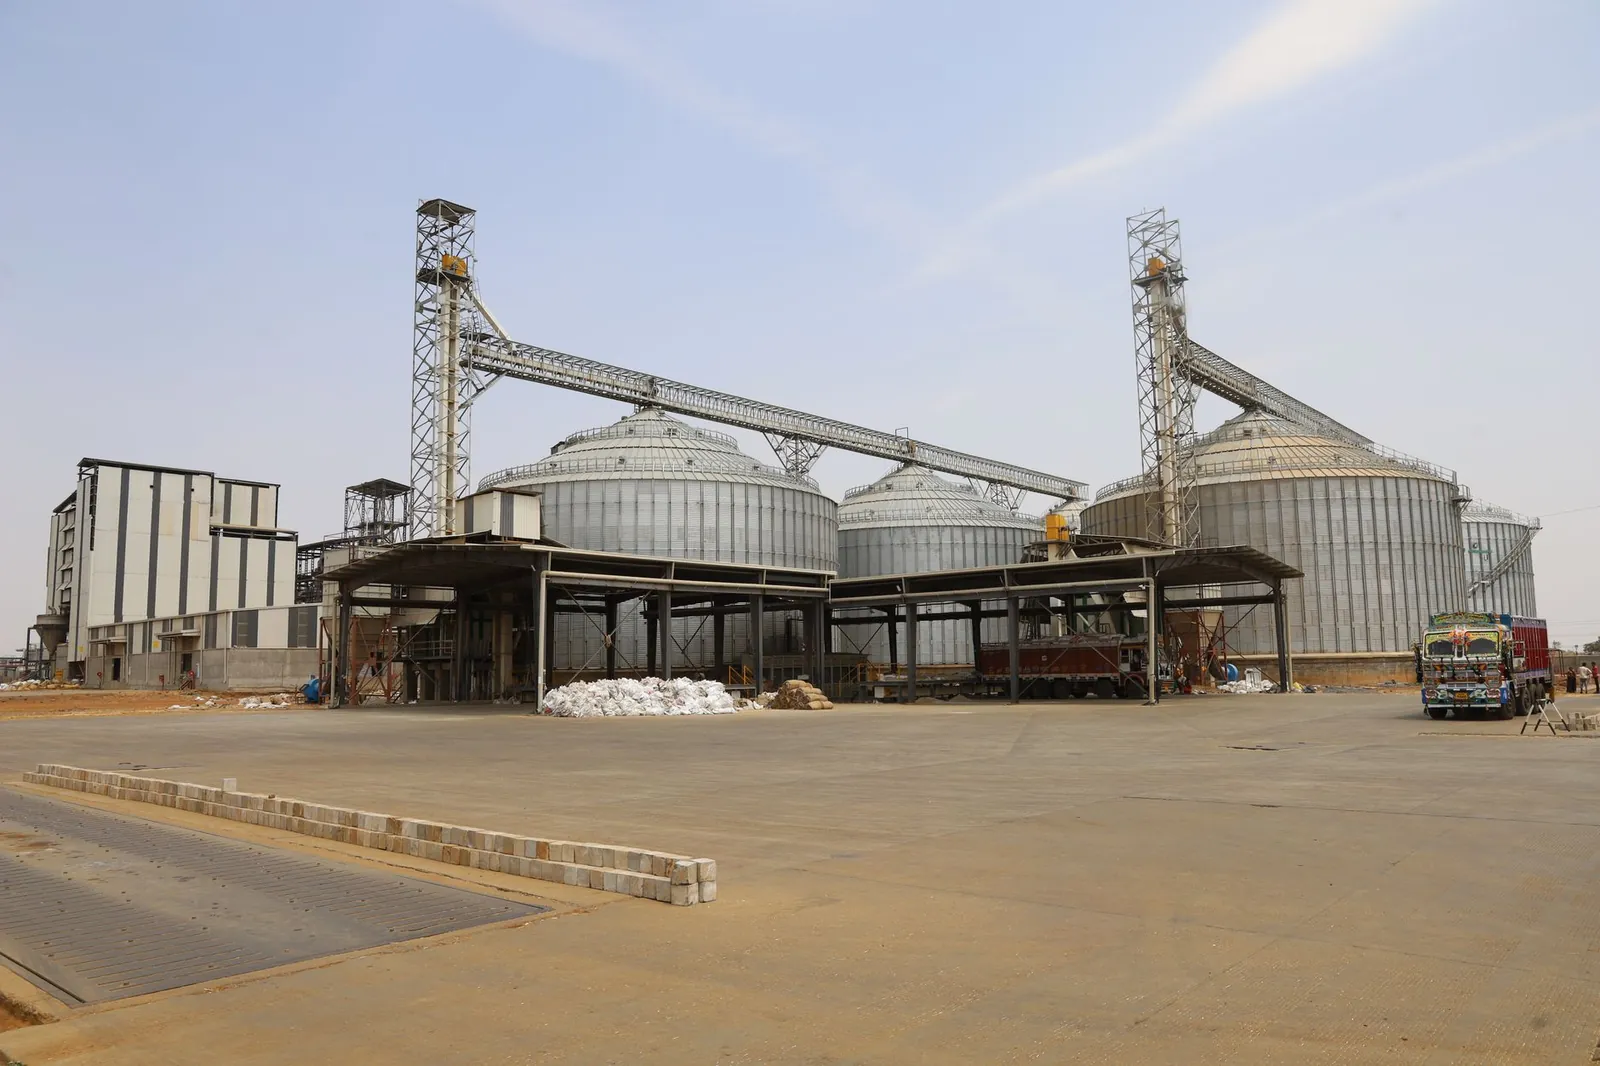
Ambuja Cements is embarking on its most ambitious expansion yet, allocating ₹14,500 crore for greenfield and brownfield projects. This deal value represents 16.9% of the company's current market capitalization and over 36% of its trailing twelve-month revenue of ₹39,865 crore. The program is designed to create a more balanced manufacturing network by strengthening the link between clinker and grinding capacity.
This move follows a period of financial pressure, with net profit for the September 2026 quarter falling 89% year-on-year to ₹193 crore. The massive capex aims to drive logistics efficiencies and reduce lead distances to high-growth markets.
Mapping the ~30 MTPA Expansion Grid
- West Cluster: 15.5 MTPA grinding additions at Mundra, Hazira, Raigad, Kalyan, Dahanu, and Amravati
- East Cluster: 11.6 MTPA grinding additions at Rangia, Hojai, Godda, and Muzaffarpur
- North Cluster: 2.9 MTPA grinding capacity expansion at Dadri Line 2 in Uttar Pradesh
- Clinker Infrastructure: 10.3 MTPA across Umrangso (Assam), Maratha (Maharashtra), and Mundra (Gujarat)
- Logistics Strategy: New units placed closer to demand centers to reduce lead distances
- Manufacturing Cost: Targeted reduction to ₹4,000 per metric ton by FY28 through efficiencies
Strategic Focus on Network Flexibility
Our next phase of expansion is focused on quality of growth and creating a more balanced manufacturing network. By strengthening the link between clinker and grinding capacity and expanding closer to the high growth potential key markets, we are building greater flexibility into the network.
Bridging the Gap to 155 MTPA by FY30
Building on recent momentum, the company added 4.6 MTPA in the first half of FY27 through expansions in Dahej, Salai Banwa, and Kalamboli. This lifted the current capacity to 113.5 MTPA. Management expects to reach 119 MTPA by March 2027 as units in Bathinda, Jodhpur, and Warisaliganj ramp up operations.
The long-term roadmap targets 149 MTPA by FY29 and ultimately 155 MTPA by FY30. These initiatives are coupled with a focus on decarbonization, including a 1 GW renewable energy investment and a partnership for zero-carbon RotoDynamic Heater technology to achieve net-zero targets by 2050.
| Date | Announcement | Amount |
|---|---|---|
| 29 Oct 2026 | Commissioned 4.6 MTPA cement capacity across Dahej (1.2 MTPA brownfield), Salai Banwa (2.4 MTPA greenfield), and Kalamboli (1.0 MTPA brownfield) unitsSource: investing.com | – |
| 12 May 2026 | Commenced construction of 2.5–4.0 MTPA cement grinding unit in Guna, Madhya PradeshSource: spglobal.com | ₹1,060.00 Cr |
| 30 Jan 2026 | Commissioned 2.4 MTPA Marwar cement grinding unit in Rajasthan, expanding capacity to 109 MTPASource: BSE filing | – |
| 01 Dec 2025 | Commissioned 4.0 MTPA brownfield clinker capacity expansion at Bhatapara, ChhattisgarhSource: ambujacement.com | – |
| 06 Oct 2025 | Announced plans to establish a port-based cement grinding unit at Adani Gangavaram Port in Visakhapatnam, Andhra PradeshSource: newindianexpress.com | – |
| 31 Jul 2025 | Expanded cement capacity to 104.5 MTPA and commissioned 57 MW wind power (lifting renewable energy capacity to 473 MW)Source: BSE filing | – |
What to watch next
- Commissioning of Warisaliganj Grinding Unit (2.4 MTPA) in Bihar during H2 FY27
- Reach total cement capacity of 119 MTPA by end of March 2027
- Completion of 376 MW Waste Heat Recovery Systems (WHRS) projects by FY28
- Next quarterly financial results announcement scheduled for early 2027
| Share price | ₹348.05 |
|---|---|
| Market capitalisation | ₹86,031.82 Cr |
| Revenue (annual) | ₹40,655.68 Cr |
| Net profit (annual) | ₹4,728.18 Cr |
| Revenue (latest quarter) | ₹9,197.00 Cr-3.19% vs previous quarter |
| Net profit (latest quarter) | ₹193.00 Cr-66.55% vs previous quarter |
| P/E (TTM) | 30.68×Sector 32.24× |
| Promoter holding | 67.33%0.00% QoQ |
| FII holding | 5.66%Current quarter |
Reference market data from a third-party provider, as of the story. Not a valuation or a recommendation.
Exchange filing by Ambuja Cements Limited announcing its next phase of expansion with ~30 MTPA capacity addition. Market figures from a third-party data provider.