| Market Cap | ₹1,003.71 CrSmall Cap |
|---|---|
| P/E TTM | 16.52Sector P/E 29.57 |
| ROE Annual | 19.37%Sector ROE 12.79% |
| Execution period | October 2026 |
| Deal value | ₹13.98 Cr |
| Share of market cap | 1.4% |
| Share of annual revenue | 4.4% |
Key highlights
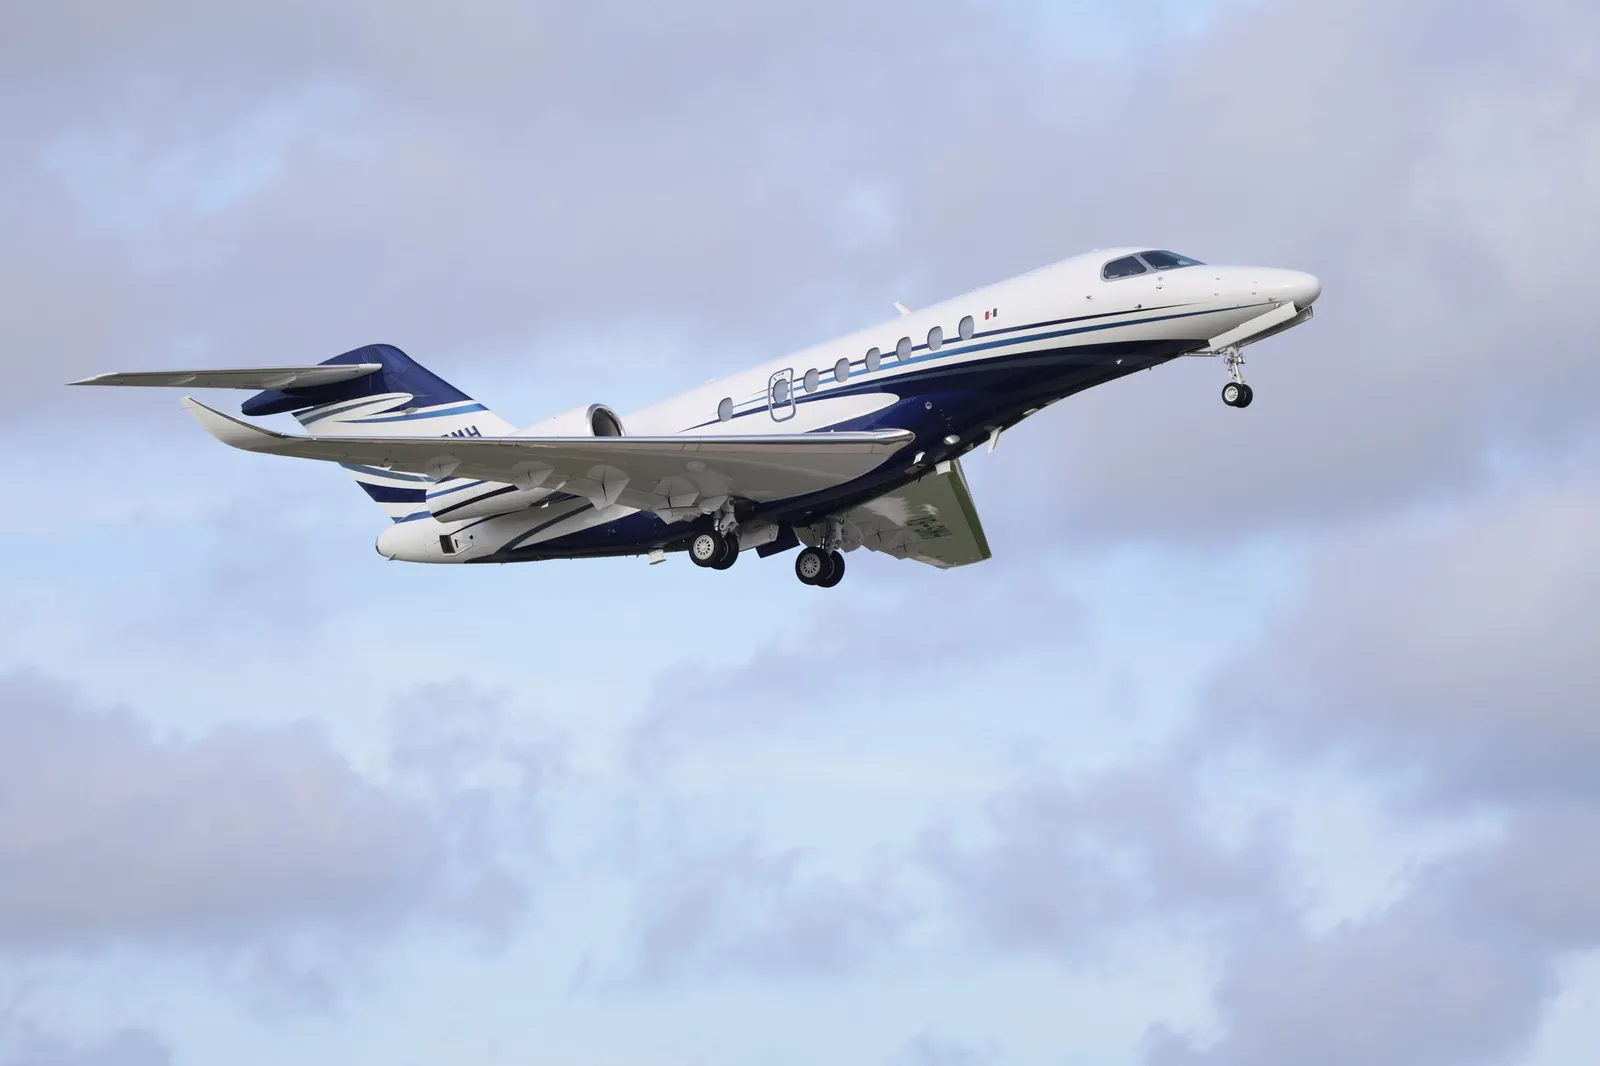
- Induction of one Hawker 900XP aircraft with a 9-passenger seating capacity
- Total investment required for the capacity addition is ₹1,398.20 Lakhs
- The acquisition is being funded entirely through the company's IPO proceeds
- Company fleet capacity grows by 50%, moving from two to three aircraft
- Projected completion for the capacity addition is within October 2026
Strategic Fleet Growth and Financial Allocation
FlySBS Aviation is utilizing its IPO proceeds to facilitate a significant jump in operational capacity. The addition of the Hawker 900XP aircraft is priced at ₹13.98 Crore, representing roughly 4.4% of the company's annual revenue of ₹318.53 Crore reported for the fiscal year ended March 2026. This investment comes at a time when the company's existing fleet of two aircraft is operating at 100% capacity utilization.
The expansion is strategically timed for October 2026, aiming to leverage the company's strong financial momentum, which saw a 113.94% year-on-year growth in annual net profit to ₹60.77 Crore.
Core Objectives of the Capacity Addition
- Enhancing the company's core operational capabilities in the private aviation sector
- Expanding existing passenger charter and specialized aviation service offerings
- Strengthening total fleet capacity to support long-term business growth
- Broadening the company's international reach through increased aircraft availability
- Providing greater operational flexibility to cater to specific customer requirements
Market Performance and Valuation Context
In the broader market context, FlySBS Aviation maintains efficient operational metrics with a Return on Assets (RoA) of 15.52%, outperforming the sector average of 7.13%. While the stock has seen a month-on-month price correction of 7.15%, its current valuation at a P/E of 16.52 remains below the industry average of 18.88. The company's promoter holding remains stable at 32.47%, with no pledged shares reported.
This fleet expansion aligns with the company's robust annual revenue growth of 71.01%, positioning the firm to capture more demand in the transportation sector where sector revenue growth is trending at 16.58%.
What to watch next
- Final induction and operational readiness of the Hawker 900XP by October 31, 2026
- Impact of increased fleet capacity on Q3 FY27 revenue results
- Updates on international service expansion following the capacity addition
| Share price | ₹580.05 |
|---|---|
| Market capitalisation | ₹1,003.71 Cr |
| Revenue (annual) | ₹318.53 Cr |
| Net profit (annual) | ₹60.77 Cr |
| P/E (TTM) | 16.52×Sector 29.57× |
| Promoter holding | 32.47%0.00% QoQ |
| FII holding | 2.27%Current quarter |
Reference market data from a third-party provider, as of the story. Not a valuation or a recommendation.
Exchange filing by FlySBS Aviation Limited announcing the revised disclosure for the induction of a new aircraft to its fleet. Market figures from a third-party data provider.