| Revenue Growth YoY | 51.3%Q1 FY27 |
|---|---|
| Total Order Book | ₹10,800 CrAs of June 30 |
| Market Cap | ₹4,058 CrMid-cap |
| PE TTM | 13.51Valuation |
Key highlights
- Revenue from operations reached ₹555 crore, representing a 51.3% year-on-year increase despite sequential seasonality.
- The energy segment now contributes 79.5% of total revenue, up significantly from previous cycles.
- Total executable order book stands at ₹10,800 crore, with energy projects accounting for ₹8,453 crore.
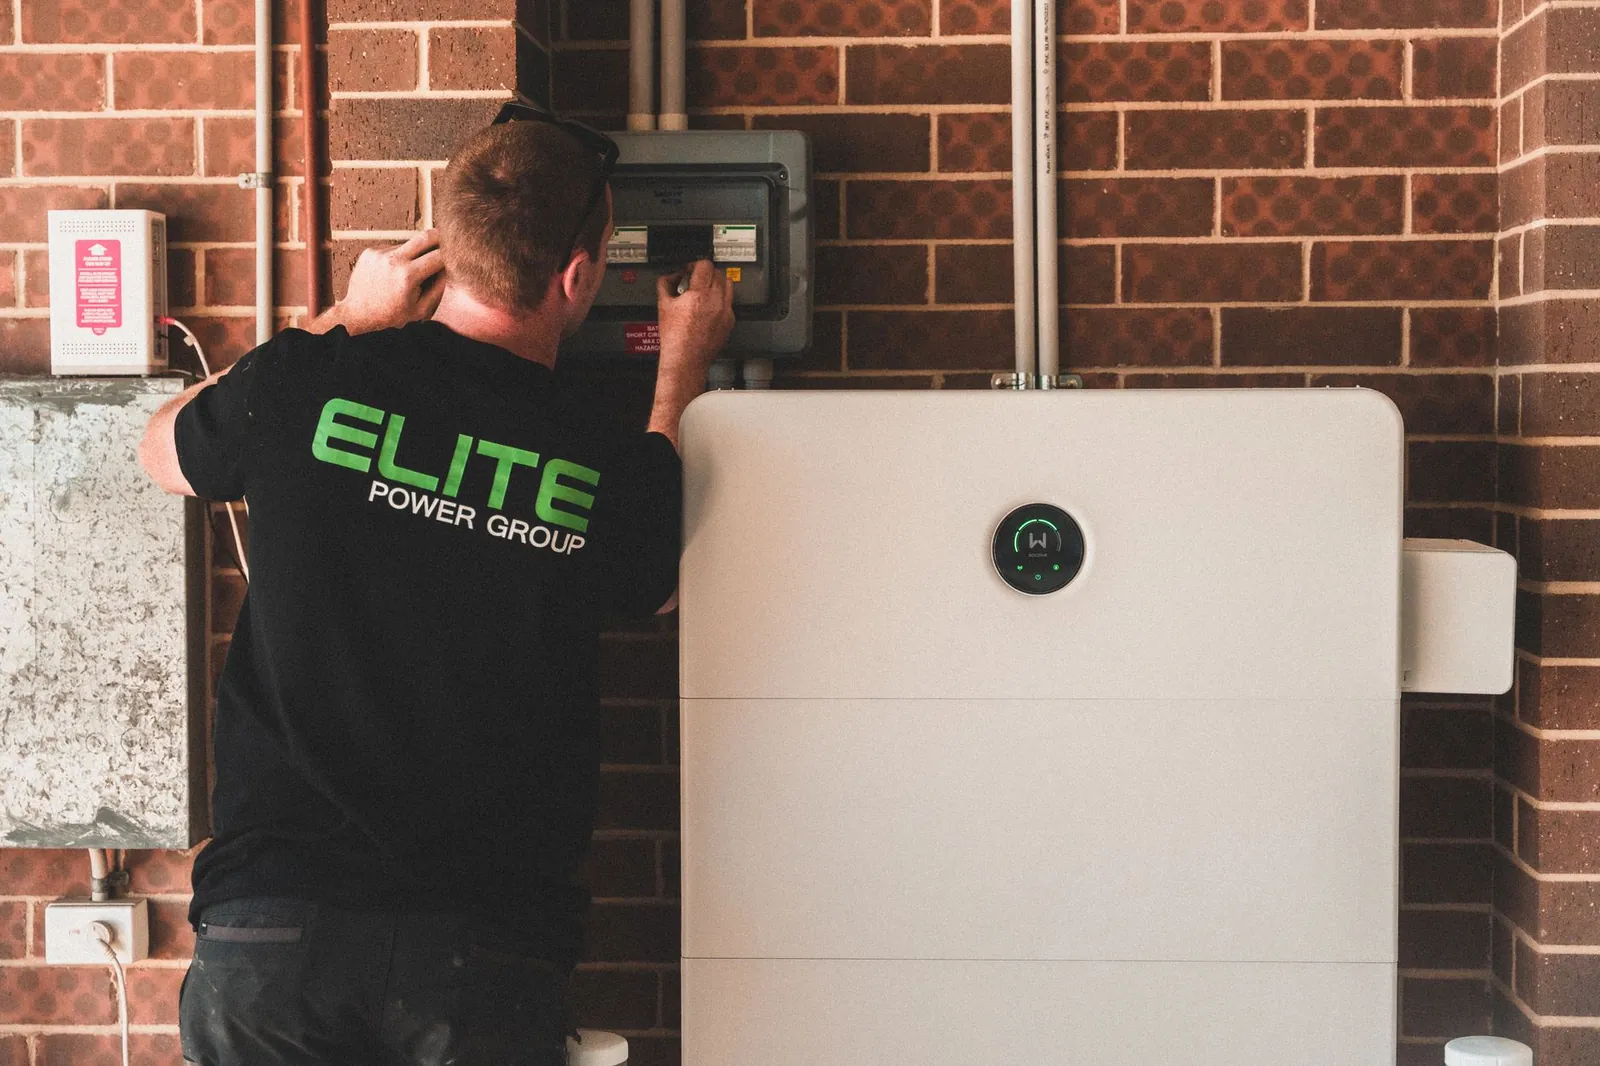
- Manufacturing capacity for battery energy storage systems (BESS) is on track to reach 10 GWh by October 2026.
- The company has initiated in-house container manufacturing to eliminate logistics bottlenecks in BESS deployment.
Financial Performance and Segment Mix
Pace Digitek recorded consolidated revenue of ₹555.36 crore in Q1 FY27, a substantial 51.29% rise compared to the same quarter last year. The energy business has emerged as the primary growth engine, contributing nearly 80% of total revenue. EBITDA margins saw a sequential improvement to 15.5%, driven by a more favorable mix of projects in the Battery Energy Storage Systems (BESS) category.
While sequential revenue declined from Q4 due to milestone-based energy project timing, management noted that H1 FY27 is expected to contribute 45% of annual revenue, improving from the 35% concentration seen in H1 FY26.
Expansion and Manufacturing Strategy
The company is executing a ₹300 crore capital expenditure plan to scale its operational capacity. Following the successful commissioning of its 5 GWh facility, Pace Digitek is adding a single 5 GWh line to reach a total of 10 GWh by October 2026. To support these operations, the company has also integrated backward by setting up an in-house BESS container manufacturing facility, which is currently undergoing trial runs.
Furthermore, the company is applying for the Production Linked Incentive (PLI) scheme for a 4 GWh cell manufacturing unit to secure long-term supply chains and reduce dependence on imported battery cells.
New Business Verticals and Order Book
- Strategic partnership with Megmeet to provide advanced power systems for AI-driven data centers in India.
- Executing key energy storage projects for major entities including SECI, KPTCL, Mahagenco, and NTPC.
- Active bidding for approximately 27 GWh of new battery storage tenders released by public sector units.
- Entering the high-margin Commercial & Industrial (C&I) battery storage segment, with initial trial orders secured.
- Research and development center in Pune led by expert scientists focused on indigenous cell chemistry.
Operational Outlook
Our energy business is taking a bigger leap compared to the telecom because of the demand which is coming up very strongly, and we are building the integrated infrastructure in both the sectors that we are into.
Future Metrics to Watch
- Commissioning of the 10 GWh capacity expansion expected between October and November 2026.
- Management's ability to maintain FY27 revenue guidance of ₹3,200 to ₹3,400 crore.
- Working capital cycle improvement in the Telecom segment, which currently remains at 150 days.
- Stabilization of lithium-ion cell pricing and its impact on contract profitability.
“We plan to reduce the revenue concentration in H2... so this year we are trying to spread between both H1 and H2.”
| Share price | ₹188.01 |
|---|---|
| Market capitalisation | ₹4,058.22 Cr |
| Revenue (annual) | ₹2,641.27 Cr |
| Net profit (annual) | ₹297.57 Cr |
| Revenue (latest quarter) | ₹555.36 Cr-49.36% vs previous quarter |
| Net profit (latest quarter) | ₹61.32 Cr-38.16% vs previous quarter |
| P/E (TTM) | 13.51×Sector 93.32× |
| Promoter holding | 69.52%0.00% QoQ |
| FII holding | 0.98%Current quarter |
Reference market data from a third-party provider, as of the story. Not a valuation or a recommendation.
Exchange filing by Pace Digitek Limited announcing its financial results for the quarter ended June 30, 2026. Market figures from a third-party data provider.