| Q1 Revenue | ₹1,581 Cr72% YoY Growth |
|---|---|
| Net Profit | ₹87.4 Cr45% YoY Growth |
| Market Cap | ₹14,122 CrGeneral Industrials |
| Working Capital | 36 DaysEfficiency Lead |
Key highlights
- Consolidated revenue from operations stood at ₹1,581 crore, a 72% increase from ₹918.4 crore in the year-ago period
- Consolidated Profit After Tax (PAT) grew 45% YoY to ₹87.4 crore, compared to ₹60.3 crore in Q1 FY26
- Operating EBITDA rose to ₹174 crore, maintaining an 11% margin despite elevated freight and tariff pressures
- Solar segment emerged as the primary growth engine, contributing 82% of the total revenue during the quarter
- Order book remains healthy at ₹2,026 crore as of June 30, 2026, providing strong revenue visibility
- Working capital cycle significantly improved to 36 days from 67 days in the previous year
Solar Segment Dominance and Capacity Ramp-up at Bhachau
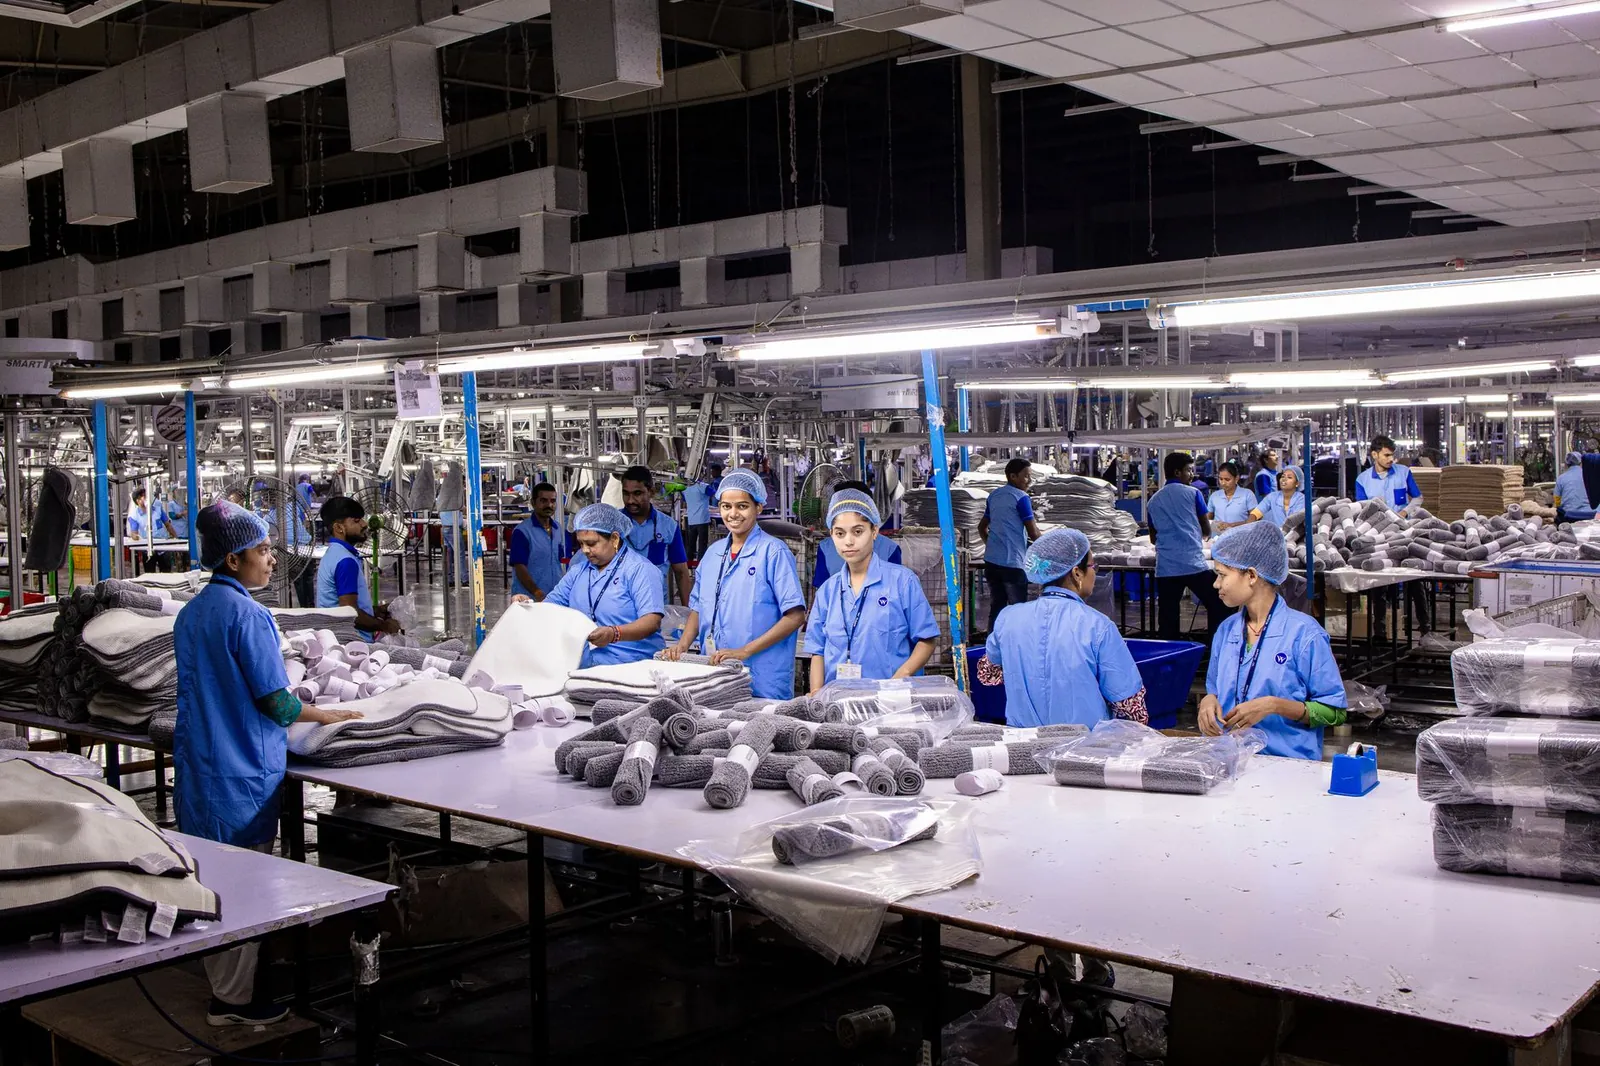
Karamtara Engineering's Q1 FY27 performance was anchored by its solar structural components business, which now dominates the revenue mix at 82%. The company reported a consolidated revenue of ₹1,580.9 crore, outperforming sector averages. A significant operational milestone was achieved with the commissioning of the new transmission line tower lattice structures facility at Bhachau, Gujarat, in Q1 FY27.
This plant is strategically located near renewable energy hubs and major ports like Mundra and Kandla. Management expects the Bhachau cluster to hit peak capacity within the next six to nine months, further bolstering the transmission vertical which currently contributes 13% of revenue.
Strategic Expansion in Saudi Arabia and Product Diversification
- Trial production at the upcoming Saudi Arabia multi-product facility is scheduled to begin in December 2026
- Commercial operations for the Saudi galvanizing plant are expected to commence by March 2027
- New PEB facility focused on data centers is slated for completion by the start of the next financial year
- Ongoing capital expenditure follows a ₹900 crore investment cycle conducted in the previous fiscal year
- The company is leveraging backward integration with 13 manufacturing facilities to maintain supply chain resilience
Navigating US Section 232 Tariffs and Global Logistics
Despite strong volume growth, Karamtara is navigating complex global trade dynamics, specifically the 50% US Section 232 tariffs on steel and aluminum products. Management noted that these tariffs are currently fully absorbed by buyers due to domestic supply shortages in the US market. However, elevated global shipping and fuel costs have impacted EBITDA margins, which stood at 11% for the quarter.
The company has secured pass-through clauses in most domestic and international long-term contracts to mitigate commodity price volatility. To sustain its growth trajectory, the company sold approximately 135,000 tonnes of product during the quarter, reflecting strong demand across 50 export destinations.
Management on Strategic Milestones
Our listing on the stock exchange is an important milestone in our journey that started almost three decades ago, and we see it as the beginning of a long-term relationship with our shareholders.
| Date | Announcement | Amount |
|---|---|---|
| 06 Oct 2026 | Q1 FY27 Consolidated Revenue from OperationsSource: angelone.in | ₹1,580.90 Cr |
| 06 Oct 2026 | Q1 FY27 Consolidated Operating EBITDASource: scanx.trade | ₹174.00 Cr |
| 06 Oct 2026 | Q1 FY27 Consolidated Profit After TaxSource: scanx.trade | ₹87.40 Cr |
| 06 Oct 2026 | Q1 FY27 Consolidated Other IncomeSource: static.hdfcsky.com | ₹3.80 Cr |
| 01 Oct 2026 | Intimation of Q1 FY27 Earnings Conference Call scheduled for 07 Oct 2026Source: scanx.trade | – |
What to watch next
- Commencement of trial production at the Saudi Arabia facility by December 2026
- Commercial operation of the PEB facility for data centers by April 2027
- Ramp-up of the Bhachau facility to peak capacity over the next 6-9 months
- Monitoring of shipping and fuel cost trends impacting H2 FY27 margins
“In FY27, we endeavor to grow our revenues by 60 to 65% over the last year.”
“As of the current quarter end, our aggregated installed capacity stood at 8,89,200 metric tons per annum, excluding rolling and galvanizing capacity used for captive consumption.”
| Share price | ₹438.8 |
|---|---|
| Market capitalisation | ₹14,121.58 Cr |
| Revenue (annual) | ₹4,311.98 Cr |
| Net profit (annual) | ₹228.75 Cr |
| Promoter holding | 82.01% |
| FII holding | 2.25%Current quarter |
Reference market data from a third-party provider, as of the story. Not a valuation or a recommendation.
Exchange filing by Karamtara Engineering Limited announcing consolidated financial results for the quarter ended June 30, 2026. Market figures from a third-party data provider.
Track Karamtara Engineering live
Get the next Karamtara Engineering filing on Telegram seconds after it lands. 15 days free.