| Revenue Growth YoY | 29.28%Decade-high Q1 |
|---|---|
| Market Cap | ₹15,908 CrCommercial Vehicles |
| Order Book | ₹16,000 CrAs of June 2024 |
| Day RSI | 63.24Neutral Zone |
Key highlights
- Revenue grew 29.28 percent YoY to ₹819.62 crore, marking the best Q1 performance for the company in ten years
- Rail & Metro segment revenue surged by 178 percent YoY, significantly contributing to the overall top-line expansion
- Defense and Aerospace vertical recorded a 25 percent growth, benefiting from indigenous procurement and new orders from HAL
- Mining and Construction segment declined 14 percent due to deferral of contract finalizations despite L1 status in major tenders
- Management identified a robust bidding pipeline worth ₹40,000 crore across various infrastructure and defense projects
Segmental Performance and Turnaround
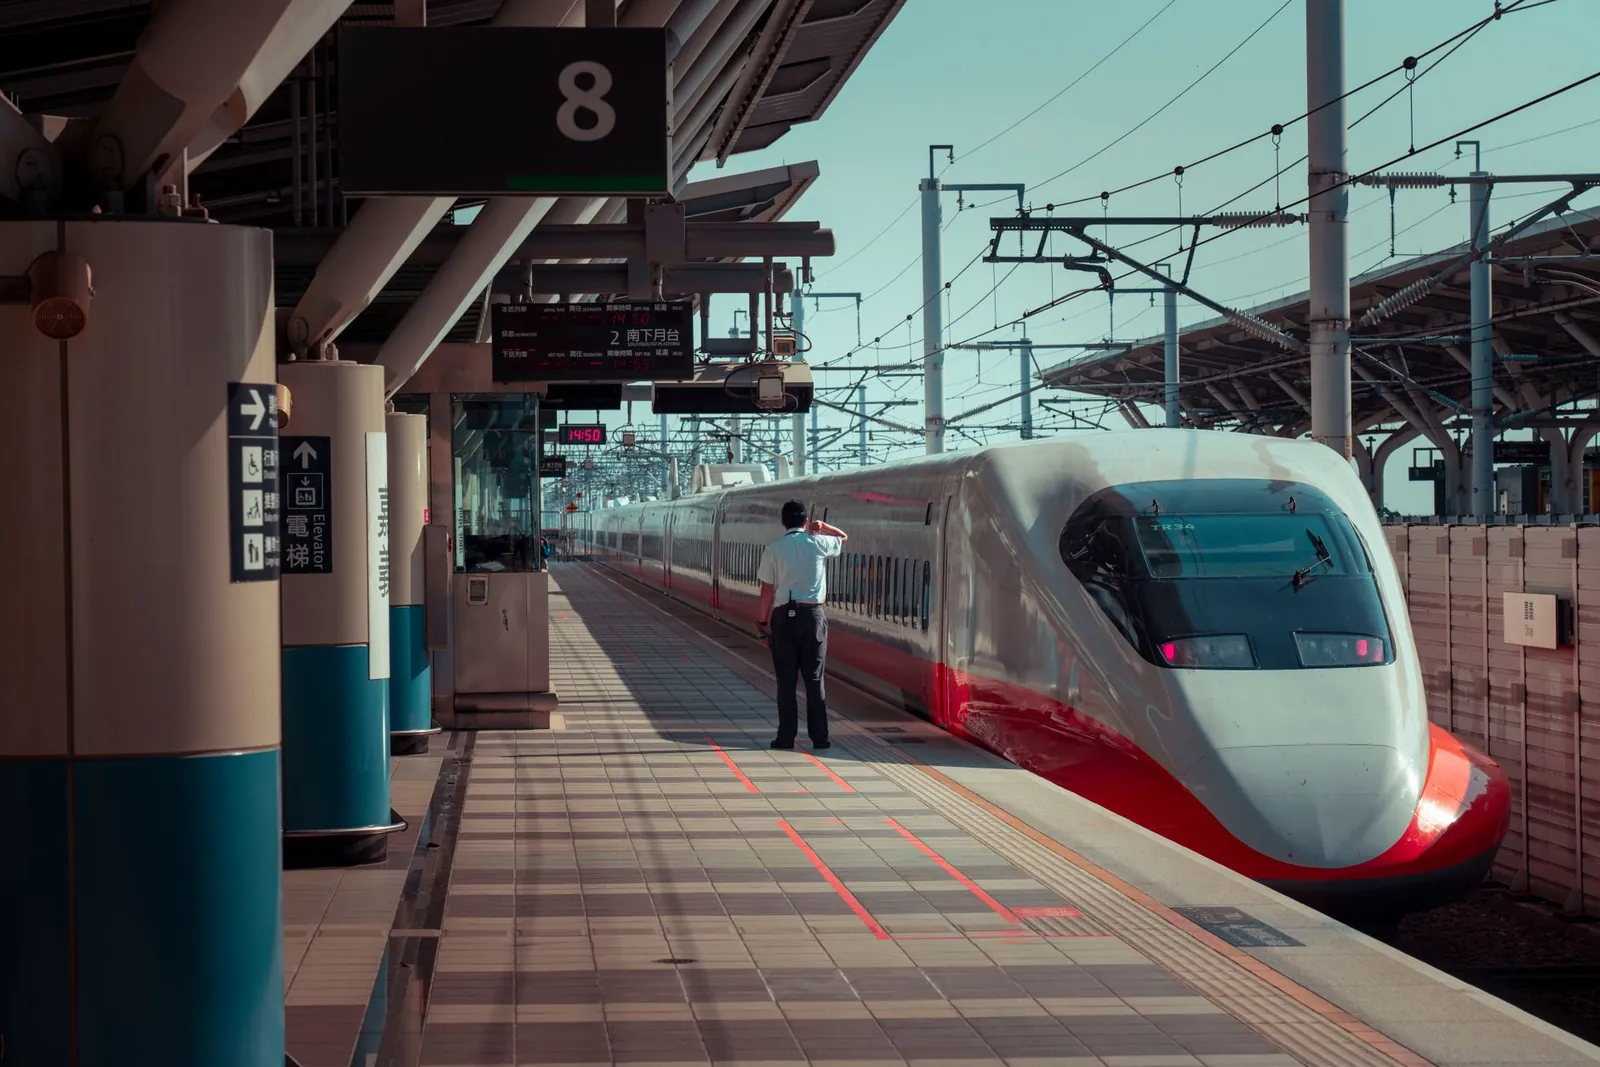
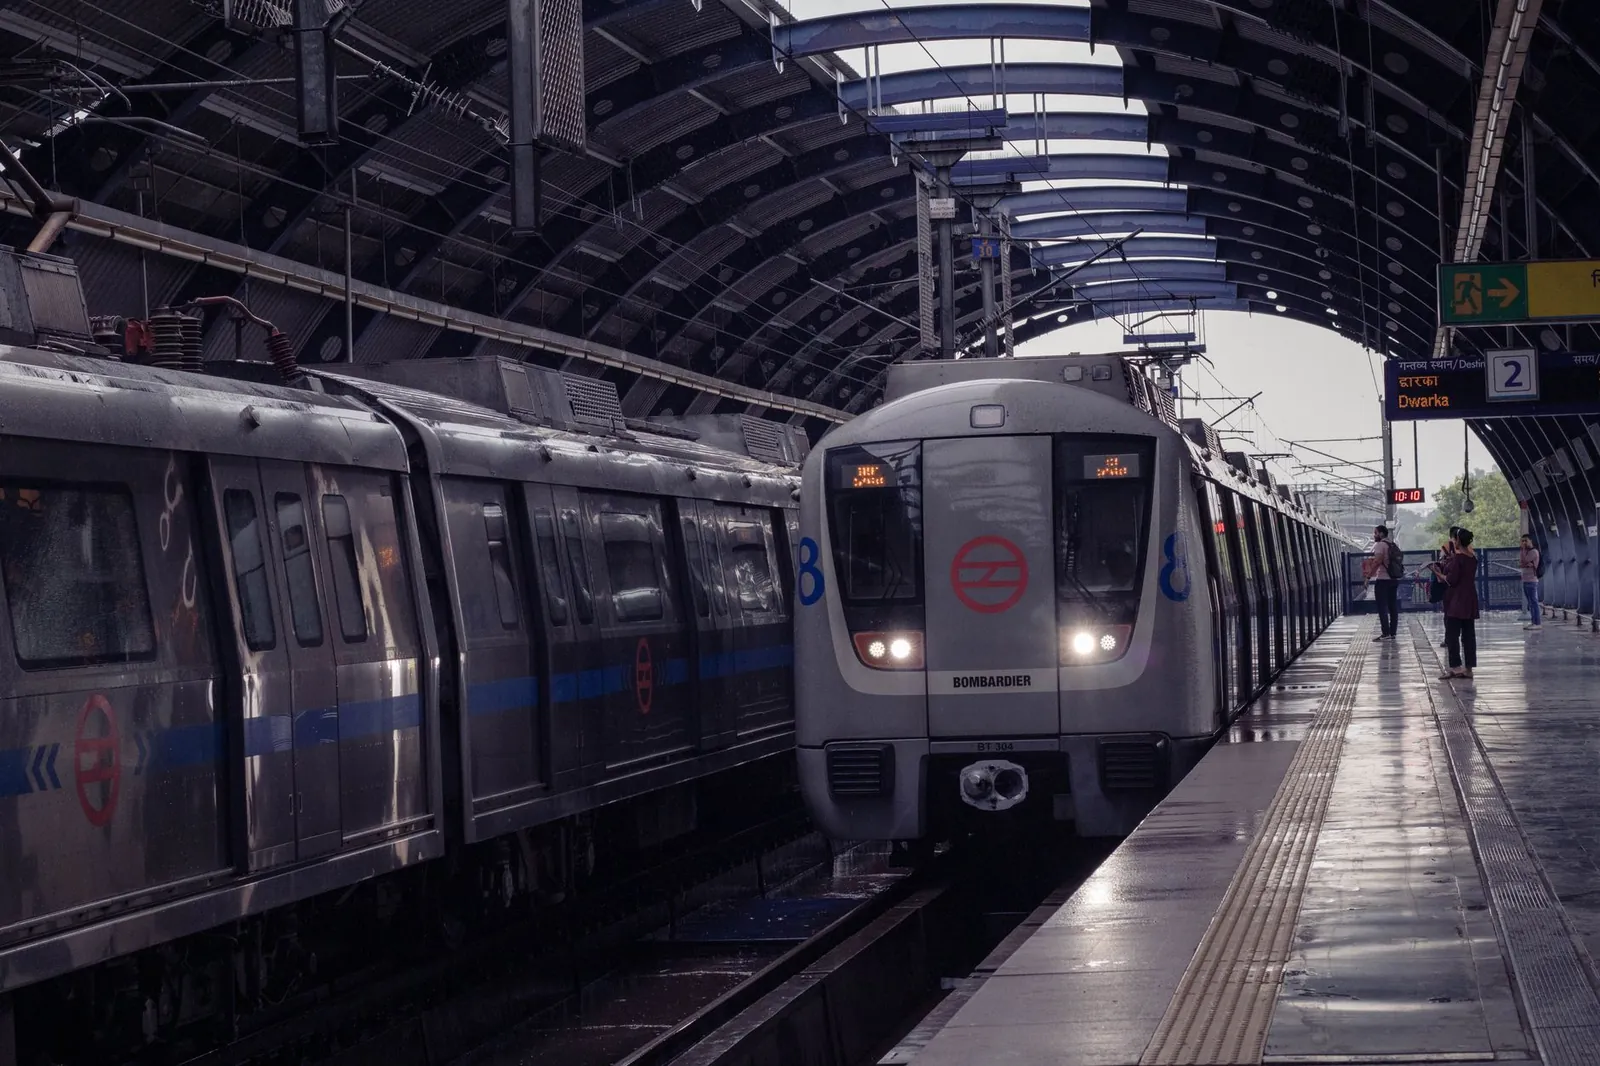
BEML's performance during the first quarter was characterized by a sharp divergence across its three primary business verticals. The Rail & Metro division acted as the primary growth engine, with revenue jumping 178 percent YoY. This was supported by progress in LHB coach production and the high-speed train project.
The Defense and Aerospace segment also performed well, growing 25 percent YoY. In contrast, the Mining and Construction segment experienced a 14 percent contraction, which management attributed to administrative deferrals in contract finalizations where the company is already the lowest bidder.
Order Book and Bidding Pipeline
The company currently maintains an order book exceeding ₹16,000 crore, providing strong revenue visibility for the coming quarters. Beyond the existing orders, management indicated a massive bidding pipeline of approximately ₹40,000 crore. This includes various domestic metro projects in Chennai, Delhi, and Uttar Pradesh, along with significant export opportunities in the Middle East and West Asia.
The company is particularly focused on high-margin sectors such as high-speed rail and defense equipment to drive future profitability and improve working capital efficiency.
Management Outlook and Strategic Initiatives
Looking ahead to FY27, BEML management is targeting a revenue growth rate of 25 to 30 percent. A significant component of this strategy involves expanding manufacturing capabilities, with a new unit planned for Chhattisgarh near Bilaspur. This unit will focus on wheeled mining equipment to be closer to major PSU clients.
Additionally, the company is investing ₹250 crore in the 'Aditya' high-speed train complex. Management expects EBITDA margins to stabilize around 13 percent as operating leverage improves through higher volume execution and increased value-addition per employee.
What to Watch
- Execution of the ₹15,000 crore export opportunities currently being pursued in the metro sector
- Finalization of orders for 16 train sets for the 280 kmph indigenous high-speed rail project
- Progress on the development of the Bhopal plant and its debt financing arrangements
- Improvement in working capital cycle, specifically reduction in inventory and debtor levels
- Recovery in the Mining and Construction segment through the finalization of deferred tenders
Management on Decade-High Growth
The last quarter has been quite an improvement, probably the best first quarter we have had in the last decade or so with a top line growth of 29%. This growth was led by a tremendous turnaround in the Rail and Metro segment.
“The first time probably again we have hit a positive EBITDA ever and the overall loss has gone down by almost 50%.”
“Our aspiration to grow, it should be around 65% to 70% Rail Metro and Defense and 30% HEMM.”
| Share price | ₹1910 |
|---|---|
| Market capitalisation | ₹15,908.20 Cr |
| Revenue (annual) | ₹4,350.53 Cr |
| Net profit (annual) | ₹141.36 Cr |
| Revenue (latest quarter) | ₹819.62 Cr-54.32% vs previous quarter |
| Net profit (latest quarter) | -₹27.01 Cr-115.02% vs previous quarter |
| P/E (TTM) | 89.15×Sector 35.36× |
| Promoter holding | 54.03%0.00% QoQ |
| FII holding | 5.48%Current quarter |
Reference market data from a third-party provider, as of the story. Not a valuation or a recommendation.
Exchange filing by BEML Ltd announcing the transcript of the Q1 FY25 earnings conference call. Market figures from a third-party data provider.