 ALFA Finder
| 1-Year Price Change | 179.16%Outperforming sector |
|---|---|
| P/E Ratio (TTM) | 23.1xSector PE: 42.6x |
| RSI (14-Day) | 50.45Neutral zone |
| Promoter Holding | 60.18%No change QoQ |
| Metric | Q2-27 | Q1-27 | Q2-26 |
|---|---|---|---|
| Revenue from Operations | 250 | 188 | 176 |
| Other Income | 23.1 | 9.4 | 7.0 |
| Total Income | 273 | 198 | 183 |
| Profit Before Tax | 71.9 | 37.5 | 21.6 |
| Net Profit | 52.5 | 29.6 | 16.6 |
| Operating Margin | 26.4% | 19.0% | 11.8% |
| Net Profit QoQ | +77.4% | ||
| Net Profit YoY | +216.3% | ||
| Adj. Profit QoQ | +73.7% | ||
| Adj. Profit YoY | +234.2% | ||
Key highlights
- Consolidated net profit reached ₹52.5 crore, up from ₹16.6 crore in the same quarter last year
- Revenue from operations grew 42% YoY to ₹250 crore against ₹176 crore in Q2-26
- Operating margins expanded by 1,460 basis points YoY to reach 26.4%
- Other income for the quarter stood at ₹23.1 crore, rising from ₹7.0 crore in the previous year
- Profit Before Tax (PBT) stood at ₹71.9 crore for the quarter ended September 30, 2026
Operating Performance and Margin Expansion
Modern Insulators Ltd saw its consolidated revenue from operations rise to ₹250 crore in Q2 FY27, a 42% increase from ₹176 crore in the corresponding quarter of the previous year. This growth was accompanied by a sharp improvement in profitability, with the operating margin expanding significantly to 26.4% from 11.8% YoY. The company reported a consolidated net profit of ₹52.5 crore, up from ₹16.6 crore in the year-ago period.
Sequential momentum remained strong as net profit rose 77.4% from the ₹29.6 crore recorded in Q1 FY27, supported by a 33% growth in top-line revenue over the same period.
Segment Revenue Distribution
- Insulators segment revenue contributed ₹219.98 crore to the total consolidated top-line
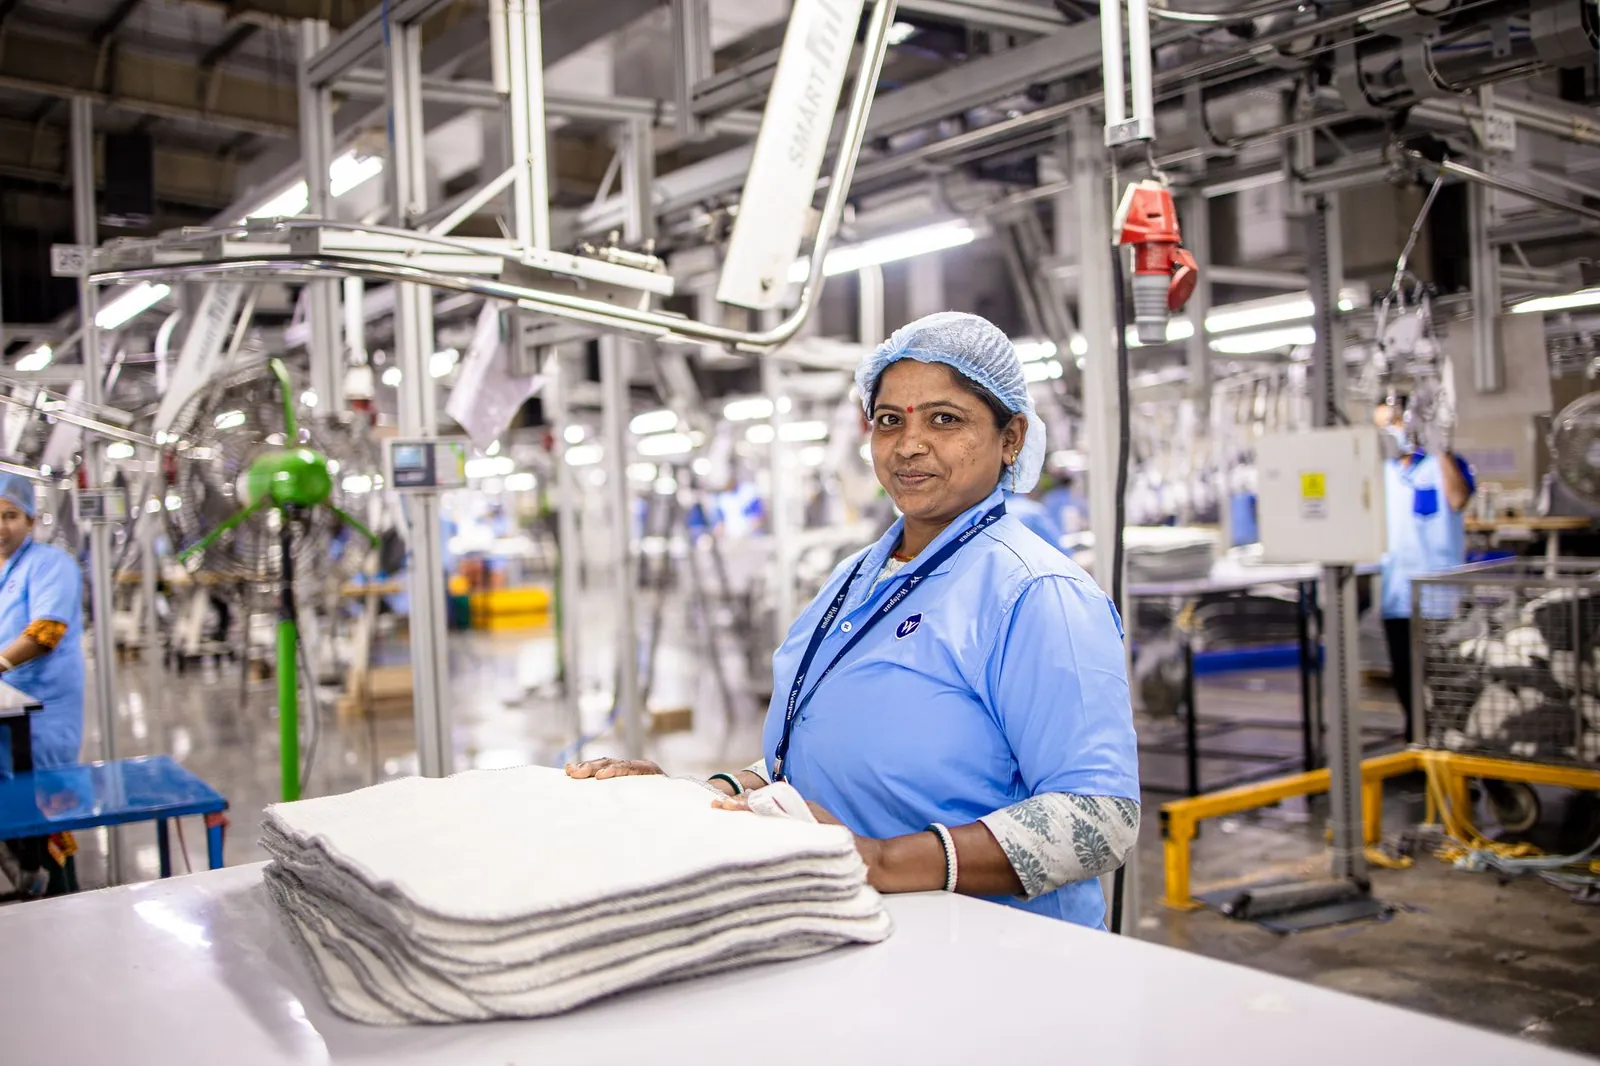
- Terry Towels division recorded quarterly revenue of ₹19.33 crore
- Other business segments generated ₹10.55 crore during the September quarter
- Insulators division profit before tax and interest stood at ₹74.24 crore
- Terry Towels segment result remained marginally positive at ₹0.03 crore for the quarter
Amalgamation Status and Auditor Qualification
The statutory auditors issued a qualified report regarding the non-provision of taxation including interest. Following a 22 January 2026 NCLT order, the company is in the process of re-submitting its application for a No Objection Certificate from stock exchanges regarding its Scheme of Arrangement with Modern Denim Limited. Due to the proposed amalgamation, tax provisions of ₹2.79 crore for the quarter and ₹5.55 crore for the half-year have not been made.
The cumulative unprovided taxation liability up to the current financial year is estimated at ₹133.35 crore, according to the management notes in the filing.
Merger Approvals and Management Outlook
Upon compliance of these regulatory requirements, in accordance with the Hon'ble NCLT order, the company will re-approach the Hon'ble NCLT for obtaining final approval of the modified Scheme. The management is hopeful that the Scheme will be approved by the Hon'ble NCLT.
| Date | Announcement | Amount |
|---|---|---|
| 10 Feb 2026 | Q3 FY26 consolidated net profitSource: perivis.com | ₹24.13 Cr |
| 06 Nov 2025 | Q2 FY26 standalone net profitSource: BSE filing | ₹17.53 Cr |
| 14 Aug 2025 | Q1 FY26 standalone net profitSource: BSE filing | ₹16.14 Cr |
| 28 May 2025 | Q4 FY25 standalone net profitSource: scanx.trade | ₹9.10 Cr |
What to watch next
- Final approval from NCLT Jaipur Bench for the merger with Modern Denim Limited
- Obtaining the No Objection Certificate (NOC) from stock exchanges for the modified scheme
- Completion of the first full year of operations for subsidiary Modern Composites Pvt Ltd in FY27
- Reconciliation of tax provisions once the amalgamation proceedings are concluded
| Share price | ₹461.45 |
|---|---|
| Market capitalisation | ₹2,175.46 Cr |
| Revenue (annual) | ₹719.84 Cr |
| Net profit (annual) | ₹79.78 Cr |
| Revenue (latest quarter) | ₹188.30 Cr-7.02% vs previous quarter |
| Net profit (latest quarter) | ₹29.60 Cr+24.18% vs previous quarter |
| P/E (TTM) | 23.1×Sector 42.65× |
| Promoter holding | 60.18%0.00% QoQ |
| FII holding | 0.31%Current quarter |
Reference market data from a third-party provider, as of the story. Not a valuation or a recommendation.
Consolidated financial results for the quarter and half-year ended September 30, 2026, as filed with the BSE. Market figures from a third-party data provider.