| Latest Quarter Revenue | ₹1,555.51 Cr34.5% YoY Growth |
|---|---|
| Market Cap | ₹12,962.23 CrMid-cap |
| Net Profit (TTM) | ₹362.73 CrOperating Efficiency |
| PEG TTM | 0.5Vs Sector 1.78 |
Key highlights
- Consolidated revenue for Q2 FY27 reached ₹1,555.51 crore, a 34.5% increase year-on-year
- Net profit grew 57.8% YoY to ₹105.51 crore for the quarter ended September 2026
- Confirmed order book stands at ₹1,879 crore, with 29% from EV and alternate powertrain segments
- Board approved ₹150 crore capex for a new mechatronics plant in Manesar, Haryana
- Management raised the long-term revenue target to ₹11,000 crore by FY31
Record Revenue Milestones and Segment Performance
Lumax Auto Technologies achieved a landmark in the second quarter of FY27, with consolidated revenue from operations hitting ₹1,555.51 crore. This marks the first time the company has crossed the ₹1,500 crore quarterly revenue threshold, representing a 34.5% increase over the previous year. Growth was largely propelled by the Advanced Plastics and Mechatronics segments, which saw half-yearly growth rates of 44% and 45% respectively.
Despite macro challenges like global supply chain inflation and volatile commodity prices, the company maintained momentum through a premiumization strategy and increased content per vehicle across its diverse product portfolio, particularly in passenger and commercial vehicle categories.
Order Book Resilience and Infrastructure Expansion
- The confirmed order book reached ₹1,879 crore as of October 2026, with 85% representing new business wins.
- Management approved a ₹150 crore capex for a new mechatronics manufacturing facility in Manesar, Haryana, to produce body control modules.
- Alternate powertrains, including EV and CNG components, now constitute 29% of the total order book, reflecting shifting market demand.
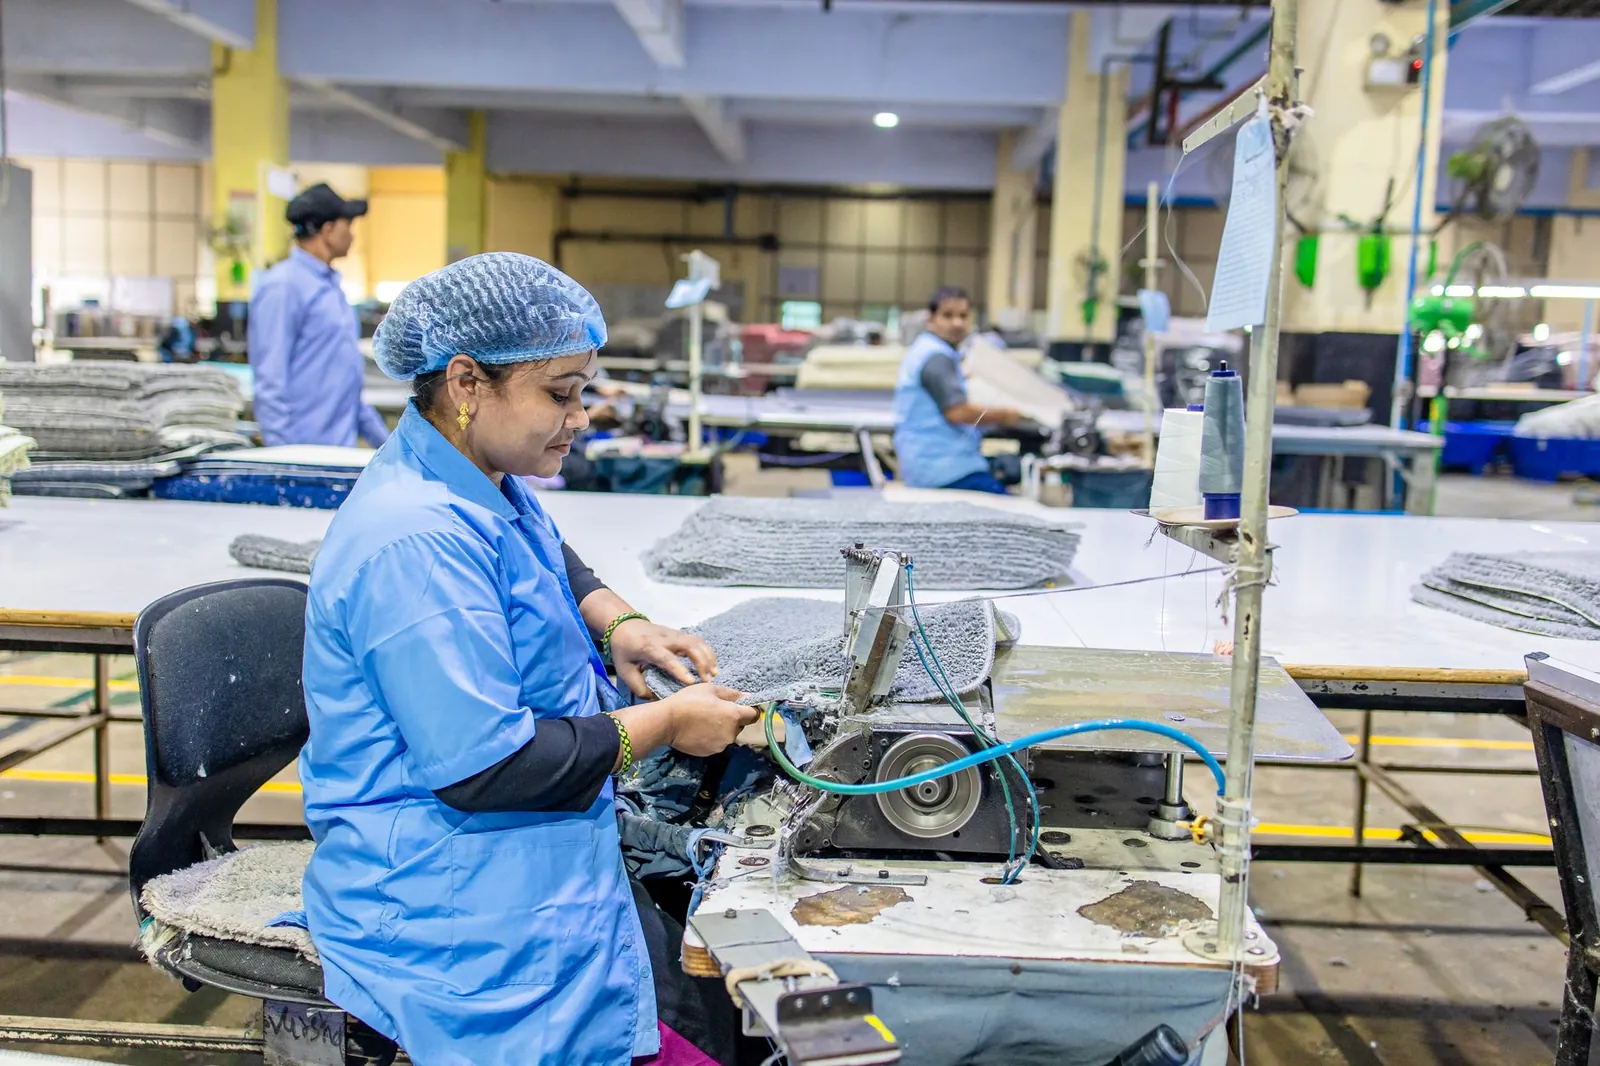
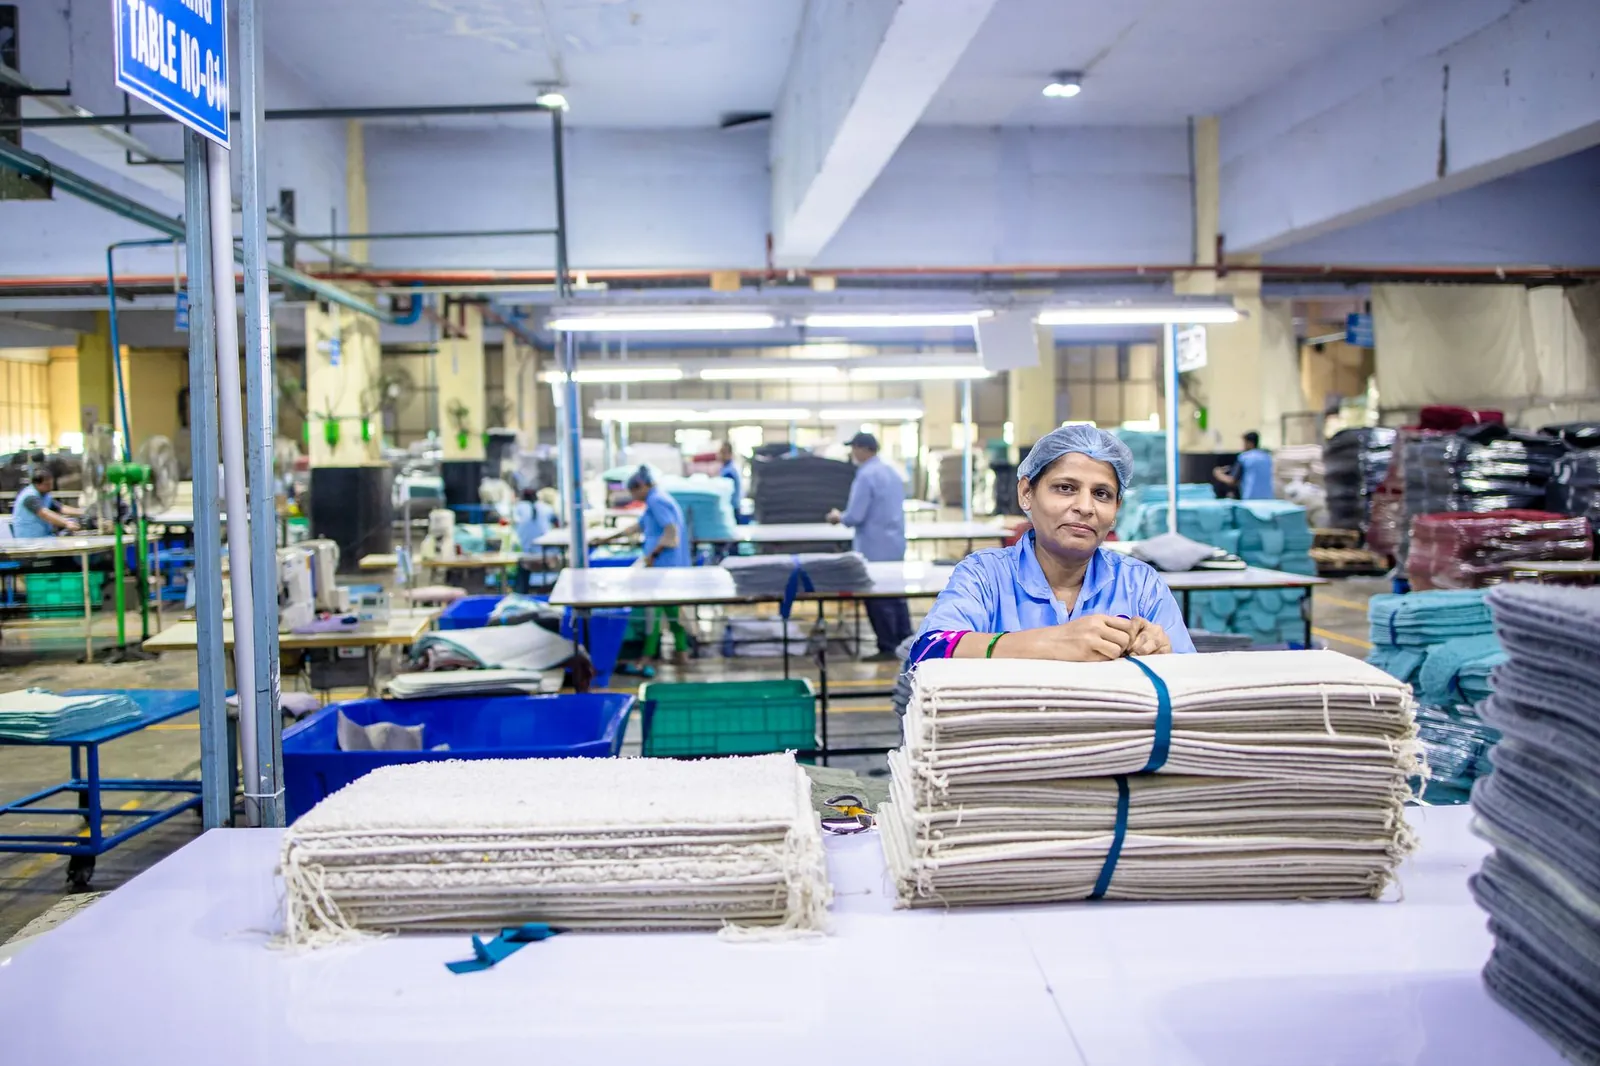
- Production successfully commenced at the Nashik facility during Q2, supplying specialized tubes and fittings to Mahindra & Mahindra.
- The company maintains a conservative debt-to-equity ratio of 0.26, providing significant headroom for the planned ₹300 crore annual capex.
- EBITDA for H1 FY27 rose 42% year-on-year to ₹434 crore, reflecting a 90 basis point margin improvement over the same period last year.
Strategic Vision for the FY31 Horizon
By FY31, we aspire to more than double our current revenue base to around 11,000 crore rupees, fueled by a blend of organic excellence and strategic inorganic opportunities.
Financial Resilience and Long-term Margin Outlook
The company reported a consolidated net profit of ₹105.51 crore for the quarter, up from ₹66.86 crore in the corresponding period last year. EBITDA margins for the first half of FY27 stood at 14.7%, slightly below the target due to rising input costs and raw material inflation. However, management remains confident in its pricing power, noting that cost pass-throughs to original equipment manufacturers (OEMs) typically occur with a one-quarter lag.
Under its 'North Star' strategy, Lumax aims to expand EBITDA margins toward 20% over the next five to seven years by focusing on high-value electronic components and mechatronics, while maintaining high capital efficiency.
| Date | Announcement | Amount |
|---|---|---|
| 24 Oct 2026 | Q2 FY27 Consolidated Revenue from OperationsSource: autocarpro.in | ₹1,555.51 Cr |
| 11 Aug 2026 | Q1 FY27 Earnings Call Management Guidance to Sustain ~15% EBITDA MarginSource: scanx.trade | – |
| 29 May 2026 | Q4 FY26 Consolidated Revenue from OperationsSource: moizz.in | ₹1,416.93 Cr |
| 12 Feb 2026 | Q3 FY26 Consolidated Revenue from OperationsSource: autocarpro.in | ₹1,270.66 Cr |
| 08 Nov 2025 | Q2 FY26 Consolidated Revenue from OperationsSource: moizz.in | ₹1,156.36 Cr |
What to watch next
- Phase 1 commercial commissioning of the Manesar Mechatronics plant, expected in Q3 FY28
- Margin recovery progress in Q3 FY27 as cost pass-throughs from Q2 are finalized with OEMs
- Execution of the ₹1,879 crore order book, with ~14% scheduled for delivery within FY27
“The overall industry production grew by 19% on a year-on-year basis to 106 lakh units, providing a healthy demand environment for our diversified product lines.”
| Share price | ₹1901.8 |
|---|---|
| Market capitalisation | ₹12,962.23 Cr |
| Revenue (annual) | ₹4,870.33 Cr |
| Net profit (annual) | ₹278.86 Cr |
| Revenue (latest quarter) | ₹1,555.51 Cr+14.07% vs previous quarter |
| Net profit (latest quarter) | ₹105.51 Cr+21.78% vs previous quarter |
| P/E (TTM) | 35.74×Sector 30.73× |
| Promoter holding | 55.98%0.00% QoQ |
| FII holding | 8.89%Current quarter |
Reference market data from a third-party provider, as of the story. Not a valuation or a recommendation.
Earnings conference call and financial results announcement for the second quarter and half-year ended September 30, 2026, by Lumax Auto Technologies Limited. Market figures from a third-party data provider.
Track Lumax Auto Technologies live
Get the next Lumax Auto Technologies filing on Telegram seconds after it lands. 15 days free.