| P/E Ratio | 97.82Sector: 51.6 |
|---|---|
| Market Cap | ₹17,098 CrGeneral Industrials |
| RSI | 40.02Neutral Zone |
| Promoter Holding | 30.8%No change QoQ |
| Metric | Q2-27 | Q1-27 | Q2-26 |
|---|---|---|---|
| Revenue from Operations | 1,132 | 861 | 822 |
| Other Income | 31.1 | 41.0 | 41.0 |
| Total Income | 1,163 | 902 | 863 |
| Profit Before Tax | 102 | 72.1 | 54.9 |
| Exceptional Items | -0.2 | -2.4 | 0.0 |
| Net Profit | 71.2 | 55.5 | 40.9 |
| Operating Margin | 8.8% | 8.0% | 6.4% |
| Net Profit QoQ | +28.3% | ||
| Net Profit YoY | +74.1% | ||
| Adj. Profit QoQ | +113.7% | ||
| Adj. Profit YoY | +415.1% | ||
Key highlights
- Net profit increased to ₹71.2 crore in Q2 FY27 from ₹40.9 crore in the year-ago period
- Revenue from operations grew 37.7% YoY to ₹1,132 crore for the September quarter
- Operating margins expanded to 8.8% in Q2 FY27 compared to 6.4% in Q2 FY26
- Board approved Machine Tool Division - Unit III in Coimbatore with a ₹10 crore investment
- Textile Machinery Division contributed ₹648.05 crore to segment revenue
- Company recorded an exceptional VRS cost of ₹2.61 crore during the quarter
Operational Performance and Segment Growth
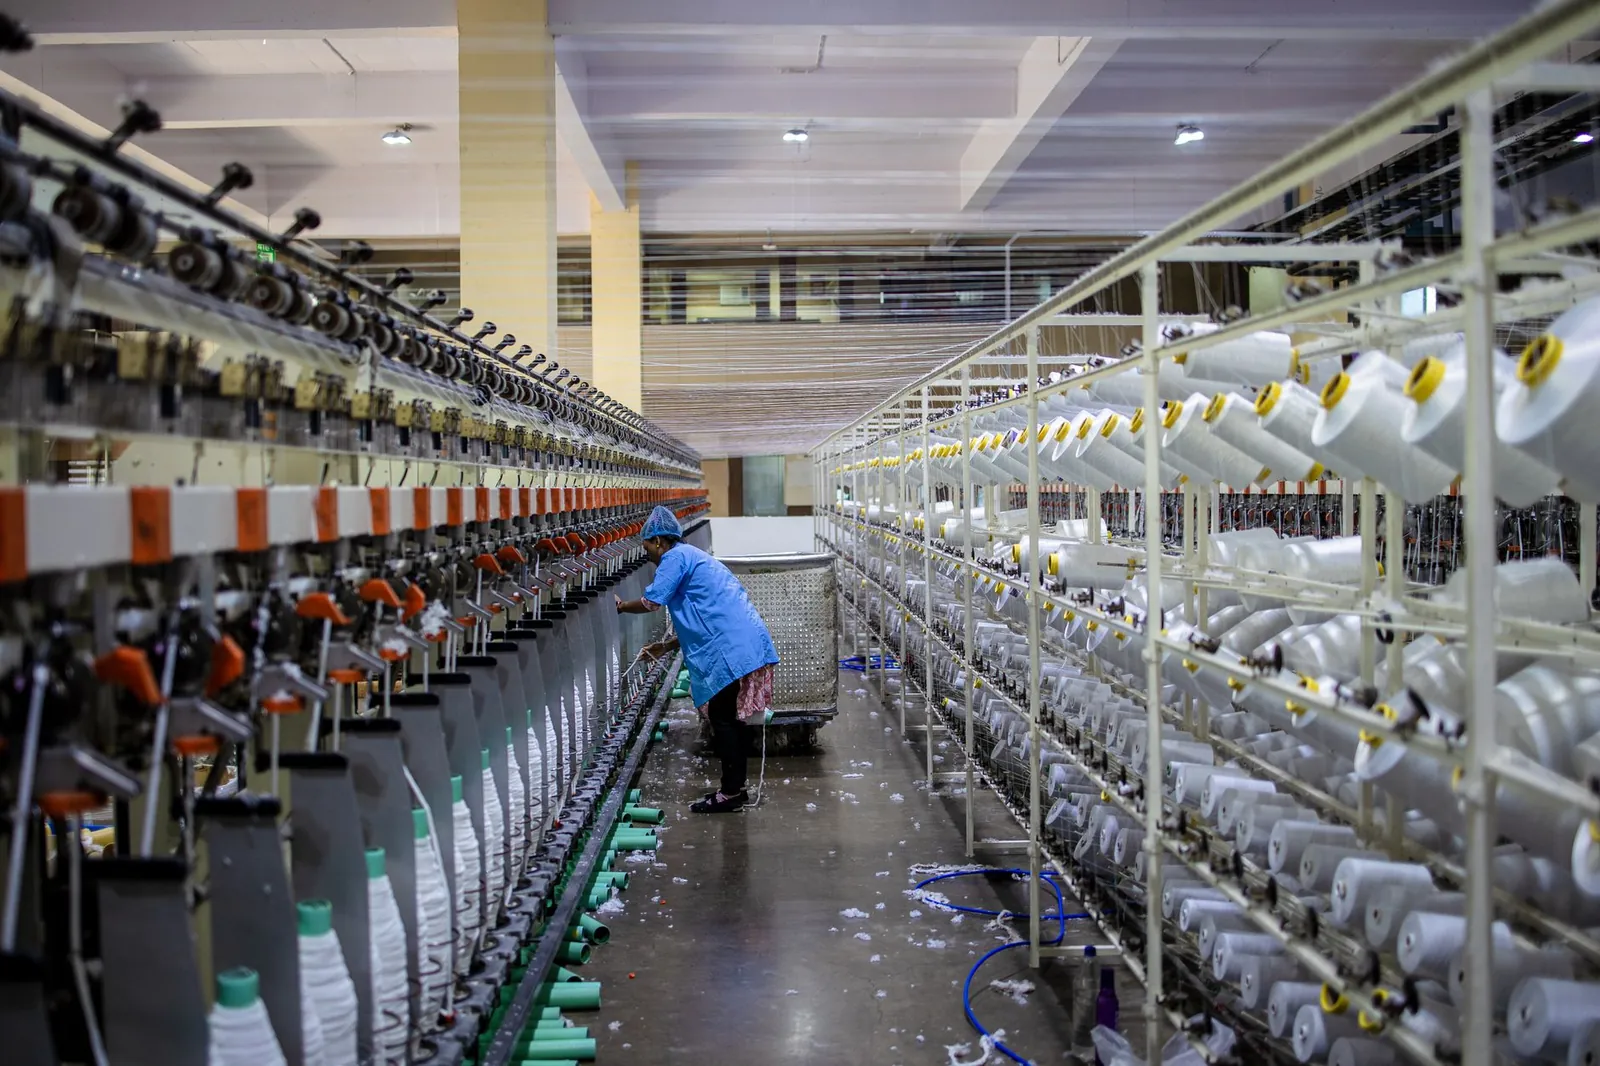
LMW Ltd reported a sharp improvement in its operational execution for the quarter ended September 30, 2026. Revenue from operations reached ₹1,132 crore, a substantial increase from ₹822 crore in the same period last year. The Textile Machinery Division led the growth with revenue of ₹648.05 crore, while the Machine Tool and Foundry Division and the Advanced Technology Centre contributed ₹451.14 crore and ₹75.59 crore respectively.
This performance follows an earlier update in July 2026 where the textile division reported a robust executable order book of ₹2,400 crore. The current quarter's success is reflected in the consolidated operating margin, which expanded by 240 basis points YoY.
Capacity Addition: A ₹10 Crore Production Expansion
- The board approved 'Machine Tool Division - Unit III' at Arasur Village, Coimbatore, to be funded via internal accruals.
- The new unit will add a capacity of 125 machines per month to address current 90% utilization levels.
- Existing capacity stands at 6,750 machines per annum, making this a significant addition to current capabilities.
- The investment of ₹10 crore aims to significantly reduce lead times for machine deliveries.
- Completion of the expansion project is targeted for December 2026.
- The unit will focus on manufacturing and assembly operations as part of a broader production expansion plan.
Profitability Trends and Exceptional VRS Costs
Net profit for the quarter stood at ₹71.2 crore, marking a 28.3% increase over the preceding quarter. This growth was achieved despite an exceptional expenditure of ₹2.61 crore towards a Voluntary Retirement Scheme (VRS) opted for by employees. The company's durability score remains high at 80, though its P/E multiple of 97.82 remains well above the sector average of 51.6.
Other income decreased slightly to ₹31.1 crore from ₹41 crore in the year-ago period. Total assets for the company stood at ₹4,907 crore as of September 30, 2026, up from ₹4,262 crore in March 2026, indicating a growing balance sheet.
Exceptional Expenditure Disclosure
The exceptional item for the quarter ended 30th September 2026 represent compensation of Rs. 2.61 Crores towards Voluntary Retirement Scheme opted by Employees.
| Date | Announcement | Amount |
|---|---|---|
| 24 Jul 2026 | Q1 FY27 consolidated net profitSource: ticker.finology.in | ₹55.52 Cr |
| 20 May 2026 | Q4 FY26 consolidated net profitSource: hdfcsec.com | ₹63.69 Cr |
| 28 Jan 2026 | Q3 FY26 consolidated net profitSource: hdfcsec.com | ₹14.66 Cr |
| 05 Nov 2025 | Q2 FY26 consolidated net profitSource: equitybulls.com | ₹40.92 Cr |
| 17 Jul 2025 | Q1 FY26 consolidated net profitSource: economictimes.indiatimes.com | ₹11.47 Cr |
| 14 May 2025 | Q4 FY25 consolidated net profitSource: equitybulls.com | ₹47.82 Cr |
What to watch next
- Retirement of Independent Director Sri Arun Alagappan effective October 25, 2026
- Operational commencement of the new Machine Tool Unit III by December 2026
- Execution of the ₹1,000 crore aerospace export order book over the next 3 years
“The new unit will reduce Lead Time for machine deliveries.”
| Share price | ₹16005 |
|---|---|
| Market capitalisation | ₹17,098.14 Cr |
| Revenue (annual) | ₹3,207.42 Cr |
| Net profit (annual) | ₹130.73 Cr |
| Revenue (latest quarter) | ₹860.72 Cr-7.76% vs previous quarter |
| Net profit (latest quarter) | ₹55.52 Cr-12.83% vs previous quarter |
| P/E (TTM) | 97.82×Sector 51.6× |
| Promoter holding | 30.8%0.00% QoQ |
| FII holding | 5.41%Current quarter |
Reference market data from a third-party provider, as of the story. Not a valuation or a recommendation.
Exchange filing by LMW Ltd announcing unaudited standalone and consolidated financial results for the quarter and half year ended September 30, 2026. Market figures from a third-party data provider.
Track LMW live
Get the next LMW filing on Telegram seconds after it lands. 15 days free.