The Product — What It Is
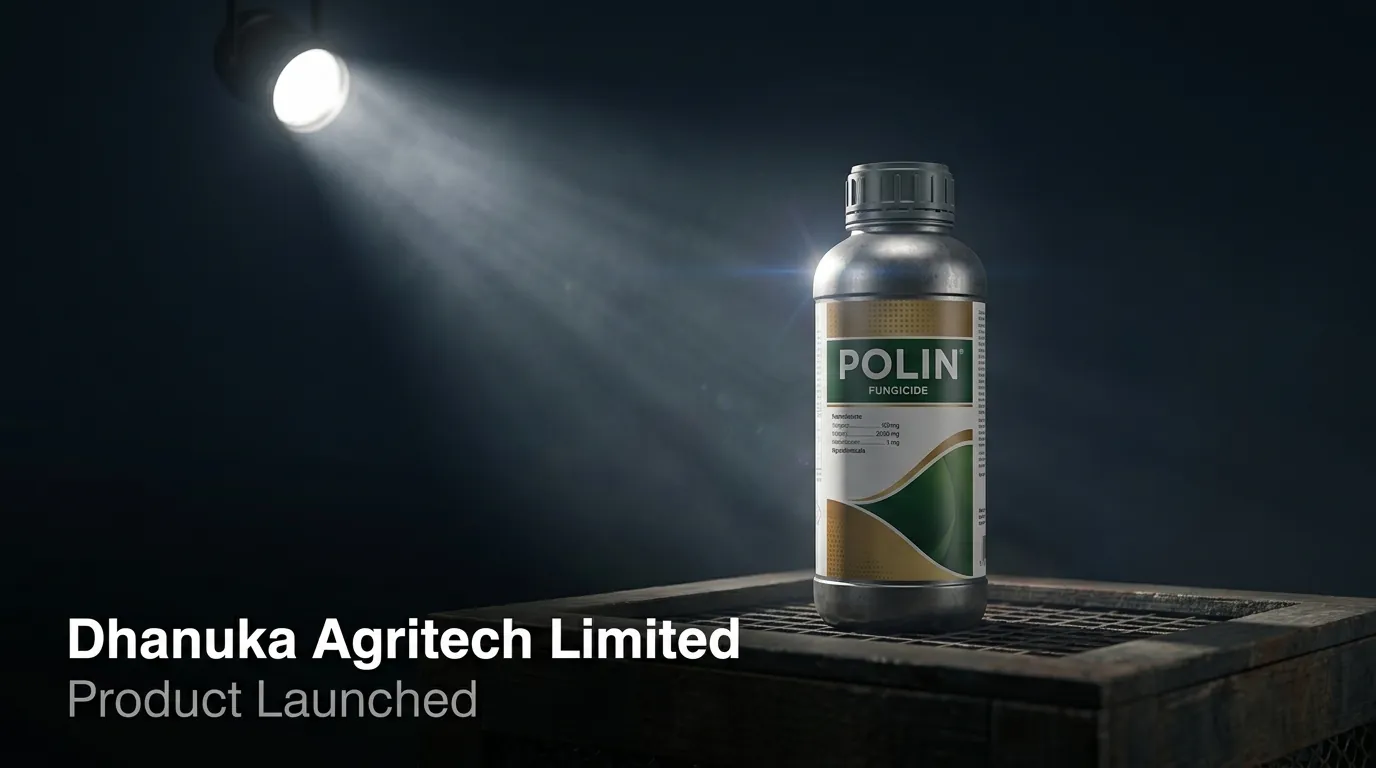
POLIN is a specialized 20% SC formulation fungicide designed to address critical fungal threats in Indian agriculture. Developed through a strategic technical partnership with Nippon Soda, Japan, the product utilizes a novel DHODHI mode of action, categorized as FRAC 52. This specific chemical classification provides a vital tool for resistance management in high-value crops.
The formulation provides preventive protection primarily against Leaf and Neck Blast, which are major causes of yield loss in paddy cultivation. Its dual translaminar and systemic action allows the active ingredients to move through plant tissues, ensuring comprehensive and longer-lasting protection against pathogens.
Commercial Opportunity
The launch of POLIN targets the extensive rice-growing regions of India, where fungal blast diseases remain a significant concern for farmers. By introducing a proprietary molecule with a unique mode of action, Dhanuka Agritech differentiates its portfolio from generic competitors. The Indian agrochemical market is currently shifting toward specialized molecules that offer higher efficacy and improved environmental profiles.
With an annual operating revenue of ₹2,019.79 crore and a robust distribution network comprising over 6,500 distributors, the company is positioned to scale the adoption of POLIN across major agricultural belts to stabilize domestic revenue streams.
Strategic Fit
- Strengthens Dhanuka's existing technical collaborations with Japanese R&D-focused chemical firms
- Expands the specialized fungicide portfolio, a key revenue driver during the kharif and rabi seasons
- Aligns with the 'Ghar Ghar Dhanuka' mission to introduce advanced global technology to Indian farmers
- Diversifies the product mix away from competitive generics into higher-margin proprietary formulations
- Addresses critical gaps in resistance management for rice-growing agricultural segments
Financial Context
Dhanuka Agritech maintains a healthy balance sheet with a market capitalization of ₹4,367.86 crore and a net profit of ₹287.23 crore for the last fiscal year. While the stock has seen a one-year decline of 37.75%, its current valuation shows a 3-year average P/E of 24.48, compared to the broader sector P/E of 38.06. The company recently reported quarterly revenues of ₹461.93 crore.
A strong promoter holding of 69.81% supports the company's long-term strategy of investing in new product launches and R&D partnerships to maintain operating margins in the face of fluctuating raw material costs.