| Total Capacity | 3.00 MTPAGrinding Limit |
|---|---|
| Market Cap | ₹372.84 CrSmall Cap |
| Revenue TTM | ₹485.13 CrLTM Performance |
| Day RSI | 36.84Near Oversold |
Key highlights
- Incremental grinding capacity of 1.18 MTPA added at the Durga Cement Works facility
- Total grinding capacity at the plant now stands at 3.00 MTPA
- Project completion follows the initial expansion proposal approved in January 2024
- Facility is located at Dachepalli in the Palnadu District of Andhra Pradesh
- Expansion supports the company's regional volume growth strategy in South India
Production Commenced — What It Means
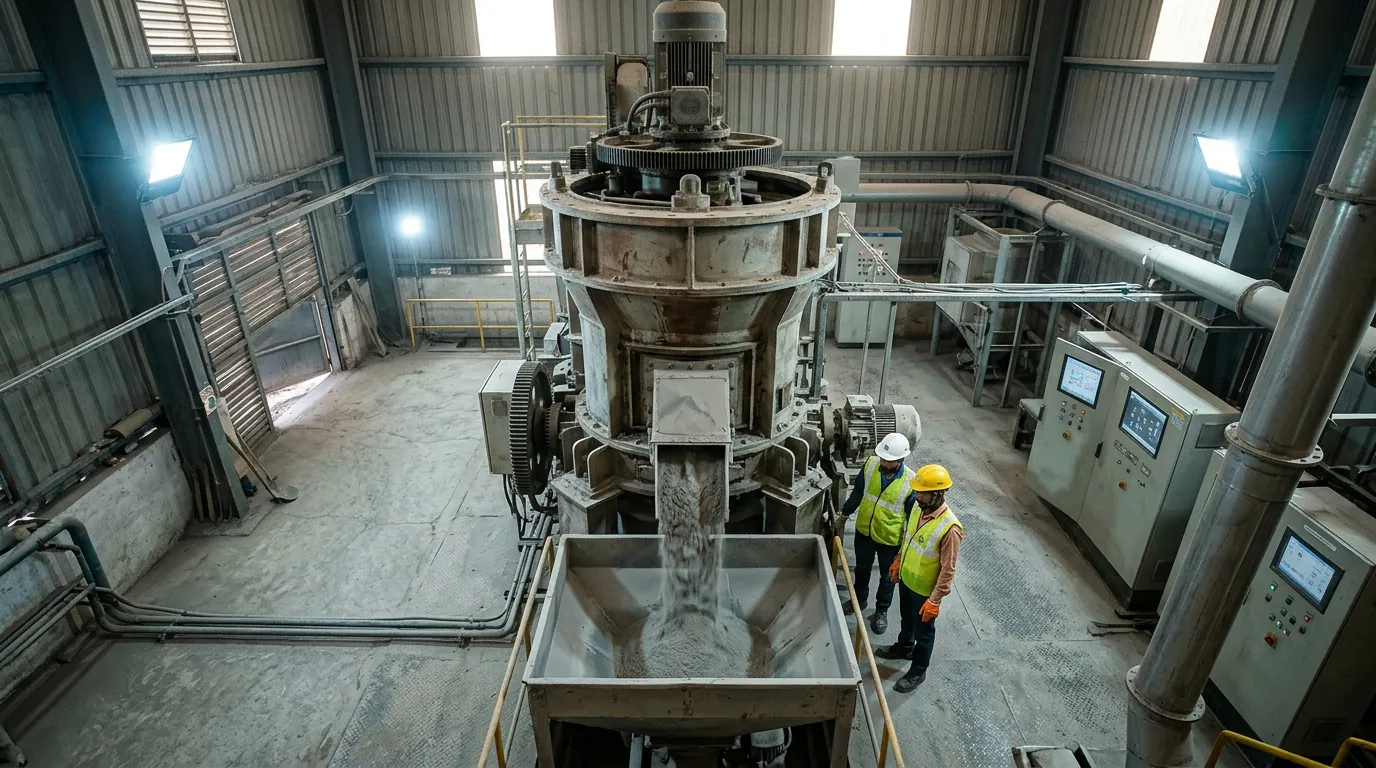
Andhra Cements has officially transitioned its expanded grinding unit at Durga Cement Works into commercial production. By scaling capacity from 1.82 MTPA to 3.00 MTPA, the company has added 1.18 MTPA of incremental output potential in the Palnadu District of Andhra Pradesh. This ramp-up is designed to cater to the rising demand for Ordinary Portland Cement (OPC) and Portland Pozzolana Cement (PPC) in the South Indian markets.
The facility, an integrated unit, now possesses a larger footprint to leverage its captive limestone resources and existing clinker manufacturing infrastructure.
Path to This Milestone
- The Board of Directors approved the capacity enhancement proposal on January 24, 2024.
- Expansion follows the company's acquisition by Sagar Cements via the NCLT resolution process in 2023.
- Infrastructure upgrades included a prior commissioning of a 6-stage preheater in October 2025.
- The project focuses on modernizing legacy assets to improve overall plant efficiency.
- Integration with parent company Sagar Cements provides operational and financial support for capital expenditure.
Financial and Operational Context
The expansion comes at a critical time as the company works toward financial recovery. For the quarter ended June 2026, Andhra Cements reported a net loss of ₹35.93 crore despite a 42.84% year-on-year increase in operating revenue to ₹142.17 crore. The increased grinding capacity is expected to allow for higher volume sales, helping to offset high fixed costs and improve capacity utilization.
While the company currently operates with a negative P/E of -5.07, the focus remains on scaling the business to reach an operating level that supports a sustainable cost structure.
Sector Tailwinds and Demand Dynamics
- Cement demand in India is projected to grow by 7-8% in FY2027, driven by housing and infrastructure.
- South Indian markets are witnessing price revisions as manufacturers manage rising freight and fuel costs.
- Regional consolidation continues as larger players absorb mid-tier subsidiaries to improve market reach.
- Increased infrastructure spending and the upcoming festive construction peak support near-term volume absorption.
| Share price | ₹40.45 |
|---|---|
| Market capitalisation | ₹372.84 |
| Revenue (annual) | ₹442.49 |
| Net profit (annual) | ₹-67.16 |
| P/E (TTM) | -5.07×Sector 32.99× |
| Promoter holding | 75%0.00% QoQ |
| FII holding | 0%Current quarter |
Reference market data from a third-party provider, as of the story. Not a valuation or a recommendation.
Exchange filing by Andhra Cements Ltd announcing the completion and commencement of commercial operations at its expanded grinding plant. Market figures from a third-party data provider.
Track Andhra Cements live
Get the next Andhra Cements filing on Telegram seconds after it lands. 15 days free.