 ALFA Finder
| P/E Ratio | 15.73Sector PE 29.33 |
|---|---|
| Market Cap | ₹643.19 CrPetrochemicals |
| RSI | 67.24Neutral Zone |
| Promoter Holding | 57.2%No Pledges |
| Metric | Q2-27 | Q1-27 | Q2-26 |
|---|---|---|---|
| Revenue from Operations | 309 | 433 | 245 |
| Other Income | 3.5 | 2.8 | 5.0 |
| Total Income | 312 | 436 | 250 |
| Profit Before Tax | 19.4 | 13.6 | 13.6 |
| Net Profit | 15.5 | 10.3 | 12.0 |
| Operating Margin | 6.2% | 3.1% | 5.4% |
| Net Profit QoQ | +50.5% | ||
| Net Profit YoY | +29.2% | ||
| Adj. Profit QoQ | +47.2% | ||
| Adj. Profit YoY | +84.9% | ||
Key highlights
- Net profit for Q2 FY27 reached ₹15.5 crore, up 29.2% from ₹12.0 crore in the same period last year
- Operating margins expanded to 6.2%, nearly doubling from the 3.1% recorded in the preceding June quarter
- Revenue from operations grew 26.1% year-on-year to ₹309 crore, led by the Ancillary Infrastructure segment
- Ancillary Infrastructure (Bitumen) segment contributed ₹206.17 crore to total consolidated revenue
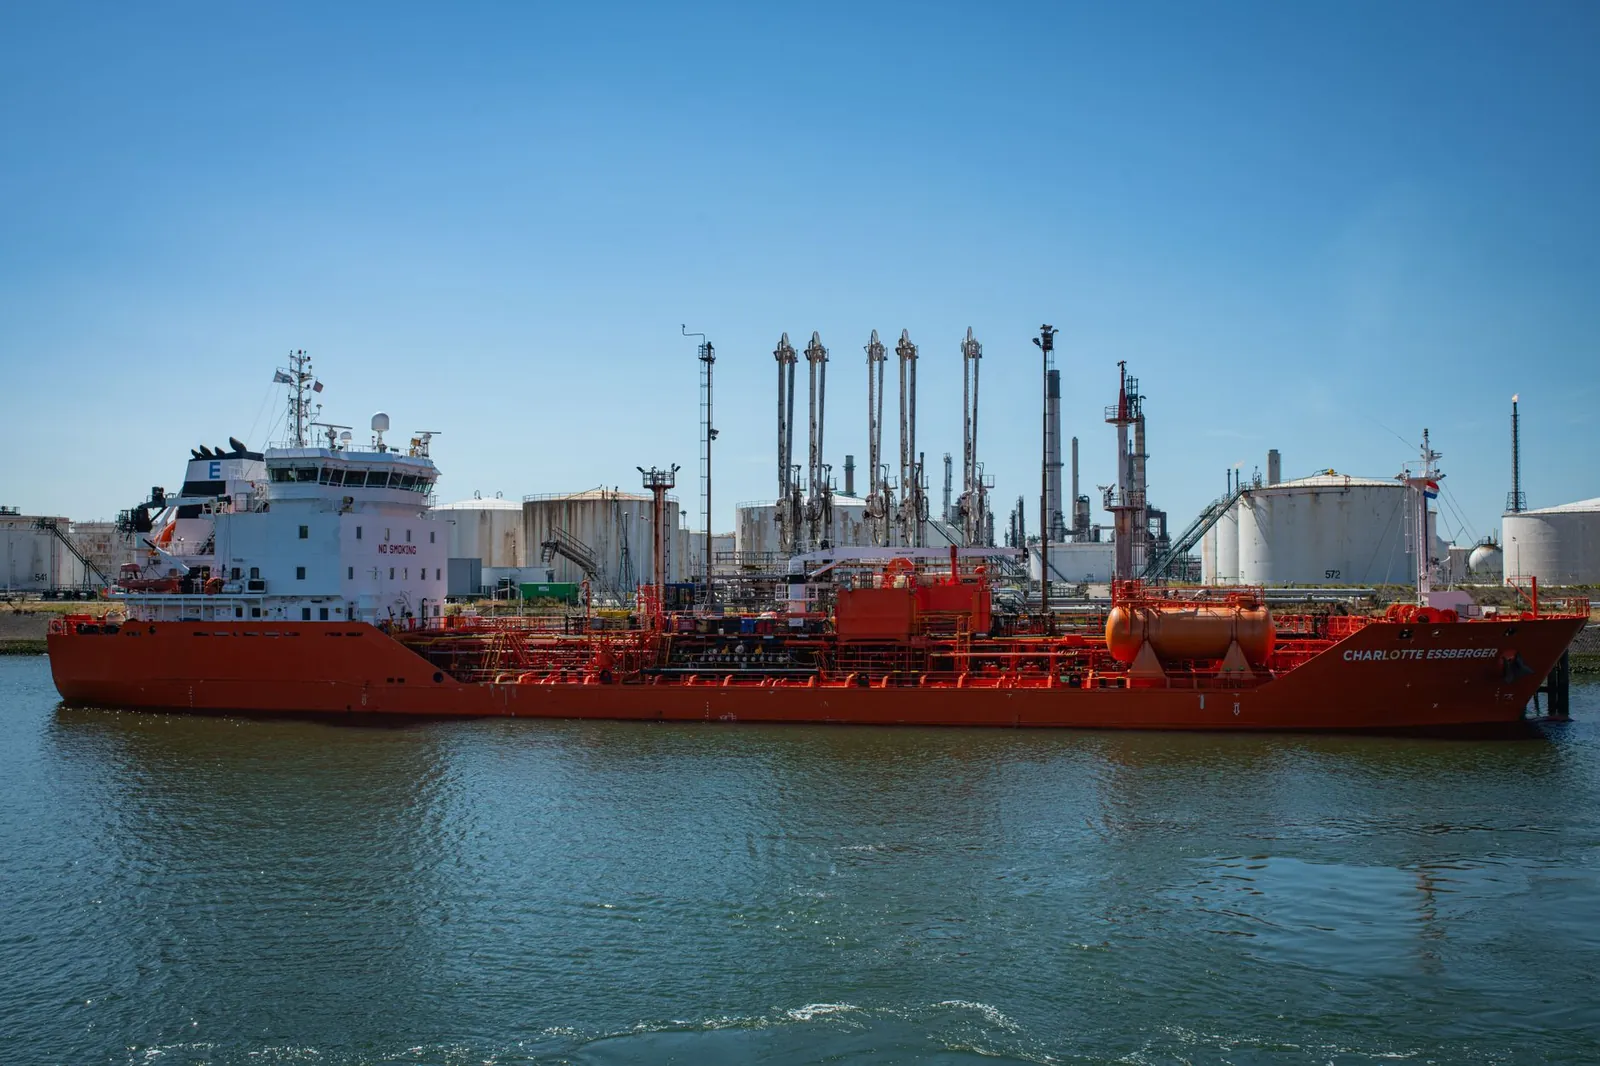
- Petroleum vessels operating and chartering segment generated ₹86.04 crore during the quarter
- Sequential net profit increased by 50.5% despite revenue declining from ₹433 crore in Q1 FY27
Operational Resilience Amidst Seasonal Revenue Fluctuations
Agarwal Industrial Corporation demonstrated strong operational efficiency in the second quarter of FY27, reporting a 29.2% year-on-year rise in net profit. While revenue from operations saw a sequential decline from ₹433 crore in Q1 to ₹309 crore in Q2, management attributed such variations to the seasonal nature of the infrastructure and bitumen businesses. The Ancillary Infrastructure segment, which focuses on bitumen and bituminous products, remained the primary driver with ₹206.17 crore in revenue.
Notably, the company successfully improved its operating margin to 6.2%, a significant recovery from the 3.1% reported in the previous quarter, indicating better cost management and segment mix.
Income Mix and Cost Composition
- Other Income contributed ₹3.5 crore to the top line, compared to ₹2.8 crore in the preceding quarter
- The Petroleum vessels operating and chartering segment contributed ₹86.04 crore to consolidated revenue
- Logistics and Petroleum Products segments added ₹8.85 crore and ₹9.80 crore respectively
- Finance costs for the quarter stood at ₹5.21 crore on a consolidated basis
- Depreciation and amortization expenses were recorded at ₹11.32 crore for the period ended September 2026
- Consolidated total assets stood at ₹1,151.83 crore as of September 30, 2026
Mitigating Geopolitical Supply Chain Risks
The Agarwal Group Companies have ensured all possible corrective measures to minimize the adverse affect of the Middle East War, primarily on the product supply, pricing framework and industry competitiveness and the Group is leaving no stone unturned towards improving operational and financial health of the Group Companies slowly and steadily.
Strategic Infrastructure Milestones and Contract Pipeline
The quarter’s performance is anchored by the company’s expanding logistical footprint, including the 40,000 MT bulk bitumen storage terminal at New Mangalore Port, which commenced commercial operations in May 2026. This terminal supports the execution of the substantial ₹477.50 crore bitumen supply contract secured from HPCL in June 2026. With a current market capitalization of ₹643.19 crore and a P/E ratio of 15.73—lower than the industry average of 18.87—the company continues to pursue its long-term target of achieving annual revenues between ₹4,000 crore and ₹5,000 crore by FY30.
Management noted that all subsidiaries, including the newly acquired Konkan Storage Systems, remain operational and unaffected by current regional conflicts.
| Date | Announcement | Amount |
|---|---|---|
| 13 Aug 2026 | Q1 FY27 Consolidated Net ProfitSource: arthasootra.com | ₹10.35 Cr |
| 29 May 2026 | Q4 FY26 Consolidated Net ProfitSource: arthasootra.com | ₹15.75 Cr |
| 14 Feb 2026 | Q3 FY26 Consolidated Net ProfitSource: tickertape.in | ₹2.80 Cr |
| 13 Nov 2025 | Q2 FY26 Consolidated Net ProfitSource: NSE filing | ₹11.99 Cr |
| 14 Aug 2025 | Q1 FY26 Consolidated Net ProfitSource: NSE filing | ₹13.03 Cr |
| 23 May 2025 | Q4 FY25 Consolidated Net ProfitSource: hdfcsec.com | ₹30.54 Cr |
What to watch next
- Execution of the ₹477.50 crore HPCL bitumen supply contract, scheduled through May 24, 2027
- Commencement of business activities at AICL Finance Private Limited following pending regulatory permissions
- Operational scale-up and utilization rates at the New Mangalore bulk bitumen storage terminal
- Progress toward the long-term revenue guidance of ₹4,000 to ₹5,000 crore by FY30
“The Basic and Diluted Earnings Per Share (EPS) has been calculated for the current and previous periods/ years in accordance with IND AS-33.”
| Share price | ₹430 |
|---|---|
| Market capitalisation | ₹643.19 Cr |
| Revenue (annual) | ₹1,652.23 Cr |
| Net profit (annual) | ₹43.57 Cr |
| Revenue (latest quarter) | ₹433.31 Cr+6.89% vs previous quarter |
| Net profit (latest quarter) | ₹10.35 Cr-34.28% vs previous quarter |
| P/E (TTM) | 15.73×Sector 29.33× |
| Promoter holding | 57.2%0.00% QoQ |
| FII holding | 2.37%Current quarter |
Reference market data from a third-party provider, as of the story. Not a valuation or a recommendation.
Exchange filing by Agarwal Industrial Corporation Ltd announcing unaudited standalone and consolidated financial results for the quarter and half-year ended September 30, 2026. Market figures from a third-party data provider.